Robert Soudný
I help companies digitize accounting processes and replace manual administration with automated workflows. With more than 20 years of experience in accounting, finance, and outsourcing, I combine deep accounting expertise with modern cloud technologies. At Wflow, my focus is helping accounting and finance teams spend less time on repetitive tasks and more time on work that creates real business value.

Robert Soudný specializes in accounting digitization, financial process automation, and the implementation of cloud technologies in finance operations. He helps organizations streamline document processing, reduce administrative workload, and gain greater visibility and control over financial processes.
After graduating in Accounting and Finance from the Prague University of Economics and Business, Robert built his career in accounting consulting, outsourcing, and financial management. In 2018, he co-founded Wflow together with David Groh, creating a platform that combines cloud technologies and artificial intelligence to automate accounting processes. Today, Wflow helps companies across Europe accelerate invoice approvals, document processing, and digital archiving.
Wflow quickly gained traction thanks to its ability to connect seamlessly with existing accounting and ERP systems while introducing efficient workflows for invoice digitization and approval. By replacing paper-based processes with digital workflows, organizations can significantly reduce administrative workload and accelerate financial operations. Today, Wflow supports customers in 18 countries, processes more than 400,000 documents every month worth over €1 billion, and is one of the leading accounting automation platforms in Central Europe.
“Just a few years ago, digital accounting processes were considered an optional advantage. Today, they have become a necessity. Automation is rapidly becoming the standard across industries because it frees both accountants and managers from routine administrative work. Over the last two years, digital transformation has accelerated dramatically and demonstrated that companies increasingly demand the most efficient tools available.”
Key Experience & Projects
- More than 20 years of experience in accounting, finance, and outsourcing
- Co-founder and CEO of Wflow
- Design and implementation of digital workflows for accounting document processing
- Automation of approval processes and financial operations
- Collaboration with accounting firms, auditors, and tax advisors
- Consulting on accounting digitization and finance team optimization
- Implementation of cloud and AI technologies in finance operations
Areas of Expertise
Accounting Digitization
- Automation of accounts payable and accounts receivable document processing
- Elimination of manual processes and reduction of errors
- Digital approval workflows
- Integration of accounting systems with modern cloud platforms
Financial Process Automation
- Optimization of accounting and approval processes
- Financial workflow automation
- Increasing finance team productivity
- Change management in digital transformation projects
Cloud Technologies & AI
- Artificial intelligence in accounting document processing
- OCR and automated data extraction
- Integration of cloud-based financial solutions
- Scaling digital finance operations
Accounting, Compliance & Regulation
- Financial management and accounting operations
- Accounting and tax compliance
- Translating regulatory requirements into practical processes
- Audit trails, compliance frameworks, and internal controls
Published articles

Digital Archiving of Accounting Documents: A Practical EU Guide
A digital archive is not simply a folder full of PDFs. A properly designed archive must allow a company to find a document years later, understand where it came from, preserve its integrity and keep it accessible throughout the required retention period.
It is therefore not the same as scanning paper documents.
The distinction is simple:
Scanning creates a file. Digital archiving creates a controlled system for preserving documents and their context.
Digital archiving is one part of a broader digital accounting environment.
Why a Folder Full of PDFs Is Not a Digital Archive
Imagine an invoice saved as: invoice_final2_corrected.pdf
The file exists.
But five years later, can you determine:
- where it came from,
- which version is authoritative,
- who reviewed it,
- who approved it,
- whether anything changed,
- which transaction or accounting entry it belongs to?
If not, you have electronic file storage.
You do not yet have a well-controlled digital archive.
The real value of archiving comes from connecting:
document + data + process history
What Does EU Law Require From Digital Invoice Storage?
There is no single European law that defines every detail of how every accounting document must be archived.
For VAT invoices, however, EU legislation establishes several important common principles.
Under the EU VAT Directive, the authenticity of the origin, integrity of the content and legibility of an invoice must be maintained from issuance until the end of its storage period.
Authenticity of Origin
The company must be able to establish who issued the invoice.
This does not necessarily mean that every invoice requires an electronic signature.
EU rules allow businesses to use business controls that create a reliable audit trail between an invoice and the underlying supply of goods or services.
Integrity of Content
The required invoice content must remain protected against unauthorised alteration.
If information changes during processing, the company should still be able to understand what happened and preserve the required evidence.
Legibility
The invoice must remain readable throughout the relevant storage period.
This becomes particularly important in long-term digital storage.
It is not enough to save a file today if the company cannot reliably retrieve and read it years later.
What Is Harmonised Across the EU — and What Is Not?
This is where the old version of this article was too simplistic.
There is no universal EU rule saying that accounting documents must be kept for five, seven or ten years.
Individual Member States determine invoice retention periods and can impose additional national requirements.
For an international company, this has a practical consequence:
retention policy cannot simply be copied from one country to another.
A digital archive should allow retention rules to be configured according to document type, company and jurisdiction.
How Long Should Accounting Documents Be Kept?
The correct answer for an EU-wide audience is:
It depends on the Member State and the type of document.
The EU VAT Directive explicitly leaves the invoice-storage period to individual Member States.
National accounting and tax rules can then impose additional retention requirements for:
- invoices,
- accounting books,
- tax documentation,
- contracts,
- payroll records,
- employment documentation,
- corporate records.
Companies operating in several markets should therefore create a retention matrix based on the jurisdictions in which they operate.
Do not rely on a generic rule such as:
“Delete everything after ten years.”
The correct retention period may differ by country and document category.
What Is a Qualified Electronic Archiving Service Under eIDAS?
European rules around electronic archiving have also evolved.
The updated eIDAS framework introduced electronic archiving as a recognised trust service.
Under the Regulation, electronic archiving means a service that handles the receipt, storage, retrieval and deletion of electronic data or documents while preserving:
- durability,
- legibility,
- integrity,
- confidentiality,
- proof of origin.
The Regulation also defines qualified electronic archiving services.
A qualified service is provided by a qualified trust service provider and must meet additional requirements designed to preserve data and documents throughout the required legal or contractual preservation period.
Documents preserved using a qualified electronic archiving service benefit from a legal presumption regarding their integrity and origin during the preservation period.
Digital Archiving Should Not Start After Accounting Ends
A common mistake is to imagine the process as:
process → post → archive somewhere
A digital archive should instead be connected with the entire document lifecycle.
For example, an invoice may move through:
receipt → extraction → validation → approval → accounting context → ERP → archive
During that process, important information is created:
- when the document arrived,
- where it came from,
- who reviewed it,
- who approved it,
- what information changed,
- which exception was handled,
- when it was transferred to accounting.
If the company archives only the final PDF, much of that context disappears.
Digital archiving therefore belongs inside the broader accounting automation architecture.
What Should Modern Digital Archive Software Be Able to Do?
Archive Documents Automatically
Users should not have to complete the accounting process and then remember:
“Now I need to save this somewhere.”
Archiving should be integrated naturally into the document workflow.
Make Documents Easy to Find
A document should be searchable using information such as:
- supplier,
- invoice number,
- date,
- document type,
- project,
- cost centre,
- accounting metadata.
An archive that technically contains a document but makes it difficult to retrieve solves only half the problem.
Preserve Documents Together With Data
An invoice is more than an image.
It contains structured information such as:
- supplier,
- amounts,
- VAT,
- dates,
- due date,
- invoice number,
- accounting context.
Connecting documents with their metadata improves both retrieval and downstream processing.
Manage Access Rights
Not every employee needs access to every financial document.
A digital archive should therefore support user roles and permissions.
Preserve Process History
For financial documents, knowing what the document looks like today is often not enough.
Companies may also need to understand:
- who worked with it,
- who approved it,
- what changed,
- when events occurred.
Connect With Accounting and ERP Systems
The archived document and accounting record should not exist as two unrelated objects.
A connected process links the document, extracted data, approval history and accounting entry.
Audit Trail, Electronic Signature and Timestamp: What Is the Difference?
These concepts are often mixed together.
They solve different problems.
Electronic Timestamp
A timestamp can provide evidence that specific electronic data existed at a particular time.
Electronic Signature
An electronic signature is used primarily to connect a signer with electronic data and to support verification of the signature.
Depending on the type of signature and the applicable law, it can have different legal effects.
Audit Trail
An audit trail records what happened during a process.
It can show, for example:
- when a document entered the system,
- who approved it,
- what was changed,
- when it moved to the next stage.
An audit trail is therefore particularly important for internal financial control.
Why Is Digital Archiving Important During an Audit?
During an audit, the question is rarely only:
“Do you have the invoice?”
The auditor may also need context:
- Who approved it?
- Which process did it follow?
- Was anything changed?
- Which transaction or accounting entry belongs to it?
- Where is the supporting documentation?
If documents, emails, approvals and accounting data are distributed across several systems, audit preparation becomes a manual investigation.
A good digital archive helps the company answer a more useful question:
Can we reconstruct what happened?
Physical Storage vs Poorly Designed Digital Storage
Paper archives have obvious weaknesses.
Documents can be:
- lost,
- damaged,
- destroyed,
- filed incorrectly,
- available only in one physical place.
But digital does not automatically mean safe.
A poorly designed digital repository can still suffer from:
- weak access controls,
- nclear document versions,
- missing backups,
- inability to demonstrate changes,
- incorrect retention or deletion rules,
- loss of context between a document and accounting data.
The right comparison is therefore not simply:
paper vs cloud
It is:
uncontrolled storage vs controlled archiving.
How to Implement Digital Archiving Step by Step
1. Map the Documents
Identify:
- which document types the company processes,
- where they come from,
- where they are currently stored,
- who uses them,
- which laws apply to them.
2. Define Retention Rules
Do not create one retention period for every document.
Build rules by:
- document type,
- legal entity,
- country,
- applicable legislation.
For international companies, this is one of the most important design decisions.
3. Define Access Rights
Access should reflect actual responsibilities.
Finance, management, accountants and auditors may require different levels of access.
4. Decide How Documents Enter the Archive
The best archive does not begin with a manual Upload to archive button.
Documents should enter the archive naturally as part of their normal workflow.
For example:
invoice received → validated → approved → accounting data prepared → archived
5. Connect Documents With Accounting Data
Avoid two disconnected worlds:
file in archive + accounting entry in ERP
Create one connected process instead.
6. Start With One Document Category
Incoming invoices are often a practical pilot because they have:
- relatively high volume,
- a clear workflow,
- accounting relevance,
- long-term retention requirements.
7. Test Retrieval
Imagine a tax authority or auditor asks for one specific invoice several years from now.
Can you find it quickly?
Can you also explain its history?
If not, the archive is not finished.
The Most Common Mistake: Creating a Digital Filing Cabinet
A company removes its paper binders.
They are replaced with:
- folders,
- subfolders,
- more subfolders,
- file names,
- manually maintained rules.
The paper disappeared.
The process did not.
That is not genuine digitalisation.
A digital archive should reduce the number of manual decisions required to store and retrieve a document.
How Does E-Invoicing Change Digital Archiving?
Structured e-invoicing changes the object being archived.
Historically, companies often thought of an invoice as a visual document:
paper → PDF
With structured e-invoicing, an invoice increasingly becomes machine-readable data.
That raises a broader question.
What needs to be preserved:
- the visual representation,
- the structured invoice data,
- related attachments,
- evidence of authenticity and integrity,
- processing history,
- accounting context?
The precise legal answer depends partly on the Member State and applicable rules.
Operationally, however, finance teams should design archiving around documents, data and context, rather than treating the invoice as a standalone PDF.
Across Europe, this becomes increasingly important as structured e-invoicing expands and ViDA pushes financial processes further towards machine-readable data.
Read more in our guide to Peppol and e-invoicing in Europe.
How Does Wflow Fit Into Digital Archiving?
In Wflow, archiving is connected to the wider accounting process.
Documents can move from receipt through AI-supported extraction and approvals into the accounting or ERP environment and remain stored together with relevant process context.
Wflow supports areas such as:
- digital document storage,
- search and filtering,
- timestamps,
- process history and audit trail,
- ser access rights,
- connection with accounting and ERP systems through ready-made integrations and an open API.
The archive therefore does not need to be an isolated endpoint.
It can remain part of the document lifecycle.
Want to Move From File Storage to a Controlled Digital Archive?
You do not need to migrate every historical document at once.
Start with one process — for example incoming invoices — and ensure that new documents are captured, processed, connected with accounting data and archived correctly from the beginning.
FAQ
What Is Digital Archiving?
Digital archiving is the controlled long-term storage of electronic documents and data so that they remain accessible, readable, protected and traceable throughout the required preservation period.
How Long Do Accounting Documents Need to Be Archived in the EU?
There is no single retention period for all EU countries.
For VAT invoices, the EU VAT Directive allows each Member State to determine its own storage period.
Other accounting, tax, corporate and employment documents can be subject to different national retention rules.
Can Accounting Documents Be Stored Electronically?
In general, electronic invoice storage is recognised under EU VAT rules.
Companies must still comply with the applicable national requirements regarding retention periods, formats, accessibility and evidential requirements.
Does EU Law Require Electronic Signatures on Archived Invoices?
No general rule requires every invoice to carry an electronic signature.
Under the EU VAT Directive, authenticity and integrity may also be supported by business controls that create a reliable audit trail between an invoice and the underlying transaction.
What Is a Qualified Electronic Archiving Service?
Under the updated eIDAS framework, a qualified electronic archiving service is provided by a qualified trust service provider and meets specific requirements for preserving electronic data and documents.
Documents preserved through such a service benefit from a legal presumption regarding their integrity and origin during the preservation period.
Is a PDF Folder in Cloud Storage a Digital Archive?
Not necessarily.
A folder can store documents, but a proper archive also needs to address retrieval, access rights, integrity, retention, process history and connection with the underlying business or accounting context.
What Is an Audit Trail?
An audit trail is the recorded history of events associated with a document or process.
It can show who processed or approved a document, what changed and when individual actions occurred.
What Is the Difference Between Digitalisation and Digital Archiving?
Digitalisation converts paper-based or manual information into electronic documents and structured data.
Digital archiving focuses on preserving those documents and data over time while maintaining their accessibility, integrity and traceability.
Sources
European Commission: VAT Invoicing
EUR-Lex: Council Directive 2006/112/EC on VAT, Articles 233 and 244–249
EUR-Lex: Regulation (EU) 2024/1183, European Digital Identity Framework / eIDAS
EUR-Lex: Implementing Regulation (EU) 2025/2532 on qualified electronic archiving services
E-Invoicing Is the Beginning. What Internal Process Comes Next?
E-invoicing changes the way an invoice arrives in a company. But the real value comes afterwards: when the invoice is correctly classified, checked, approved, enriched with context and passed into the accounting or ERP system. See how to build and automate the internal process after invoice receipt.
E-Invoicing Is the Beginning. What Internal Process Comes Next?
E-invoicing changes the way an invoice arrives in a company.
Instead of a PDF attachment in an email, it can arrive as structured data that a system can read and process automatically.
That is a major step.
For financial management, however, an equally important question is what happens to the invoice after it arrives.
Who checks it? Who approves it? Who adds the cost centre, project or accounting context? Where are duplicates, suspicious bank-account changes or missing purchase orders detected? And when do the data reach the ERP so finance can actually work with them?
Across Europe, the regulatory journey differs by country. Some Member States already require structured domestic e-invoicing, others are introducing it gradually. At EU level, ViDA will make e-invoicing the basis for digital reporting for relevant cross-border B2B transactions from 1 July 2030. Taxation and Customs Union
If you are still getting familiar with the basics, start with E-Invoicing in the EU: How Peppol Works and Why It Is About Data, Not Documents.
Here, we will look at the next step: the internal process after the invoice arrives.
The Process Does Not End When the E-Invoice Arrives
A structured invoice improves the quality of incoming data.
But it does not create the rules inside your company.
That is why the transition to e-invoicing is a good opportunity to look not only at invoice format, but at the entire document flow from receipt to accounting.
Email Is Not an Accounting Workflow
Email can receive an invoice.
It cannot manage a financial process.
It does not know who should approve an invoice. It does not check whether it matches a purchase order. It does not automatically flag a changed supplier bank account. It does not know that an invoice has been stuck with one person for five days.
And when an auditor or CFO needs to find out exactly what happened to a document, an email thread quickly stops being sufficient.
If approvals are currently scattered across email, chats and informal agreements, see how automated invoice processing can connect approval, data extraction and accounting workflow.
What Should Happen After an Invoice Arrives?
Once an invoice arrives, the document needs to be classified, its type identified, data completed or validated, routed to the right approver, checked for exceptions and prepared for transfer to the accounting or ERP system.
At Wflow, we automate this process through several layers:
1. Smart Inbox
Invoices and documents enter one controlled place instead of remaining scattered across emails, folders and other channels.
2. Classification and Categorisation
The system identifies the document type, supplier, client or other context and prepares the document for the next step.
3. Data Validation and Exception Checks
Better input data do not mean zero risk. Documents still need to be validated, compared and checked for inconsistencies before they reach accounting.
4. Rule-Based Approval
An invoice should automatically reach the right person based on amount, supplier, project, cost centre or type of expense.
5. Transfer to Accounting / ERP
The ERP remains the accounting backbone. Wflow manages the process before the approved and validated data enter the accounting environment.
For companies that want to introduce e-invoicing without replacing their existing systems, see How to Implement E-Invoicing Without Replacing Your ERP.
E-Invoicing and Wflow Accounting Autopilot
E-invoicing improves the input.
Accounting Autopilot manages what happens next.
Its purpose is not to let AI post accounting entries without oversight.
The goal is to move routine work from accountants’ desks into a controlled workflow: collecting documents, classifying them, extracting data, validating information, preparing accounting suggestions and identifying the cases where human input is required.
The accounting team therefore does not need to treat every document in the same way.
Routine cases can move faster, while attention shifts towards exceptions, control and decisions.
You can see the complete workflow in Accounting on Autopilot: AI Takes Over Routine Document Processing.
The boundary between automation and human responsibility is just as important. We cover it in detail in AI in Accounting and Responsibility for Errors.
How to Tell That Your Process Is Not Ready
E-invoicing will expose weaknesses that already exist inside the company.
The warning signs are usually simple:
- invoices get lost in inboxes,
- approvals depend on reminders,
- the accounting team still re-keys data manually,
- the CFO sees liabilities too late,
- it is unclear who approved what,
- exceptions are handled differently every time,
- ERP data only become available when it is already too late to react.
If several of these sound familiar, the problem is not the invoice format.
It is the process around the invoice.
Traceability is especially important: who approved the document, what changed, why it changed and when it moved to the next stage should not depend on somebody finding the right email.
That same principle becomes even more important as more of the process is automated. See AI in Accounting and Responsibility for Errors for more on auditability and human control.
What to Prepare Before E-Invoicing
Before introducing e-invoicing, it is worth setting up several practical things.
Not to make the process more complicated, but to ensure that a structured invoice does not simply end up in the same chaos as today’s PDFs.
- One controlled entry point for all invoices
The principle is simple: invoices should not end up in personal email accounts, random folders or several disconnected team inboxes.
The company needs one place where documents enter and where it is immediately clear what arrived, who sent it, who it belongs to and what stage it is in.
- Expense rules before the invoice arrives
E-invoicing does not solve only the invoice itself.
If the company does not know who can order a service, who approves the expense, which project it belongs to or which budget it consumes, the delay simply moves further down the process.
A prepared company manages the whole expense process, not only invoice receipt.
- Rule-based approvals instead of reminders
An invoice should automatically go to the right person based on amount, supplier, cost centre, project or expense type.
Without these rules, even a structured invoice will get stuck in exactly the same place as a PDF: someone still needs to forward it, chase an approver and explain what needs to happen.
- Checks for duplicates, changed details and suspicious cases
Automation or Accounting Autopilot can perform part of this control, but the company still needs to define what it expects the system to check.
Duplicate invoices, supplier bank-account changes, purchase-order mismatches or unusual amounts should not depend solely on the manual attention of the accounting team.
- Clear exception handling
Standard cases can gradually move through the process faster.
That makes it even more important to define what happens when something is an exception: who deals with it, what information they need, how they decide and when the document returns to the standard workflow.
Otherwise, exceptions simply move outside the system again.
- Audit trail
Knowing that an invoice arrived is not enough.
The company needs to be able to trace who approved it, what changed and why.
Without an audit trail, control still depends on people’s memory and email history.
- ERP integration
The ERP remains the accounting backbone of the company.
Preparing for e-invoicing does not mean replacing it. The objective is to deliver clean, approved and traceable data into the ERP after the workflow before accounting has been completed.
E-invoicing can be introduced without replacing the existing ERP if the integration layer is designed correctly.
- Visibility of liabilities
Design the process so finance can see not only invoices that have already been posted, but also expenses and documents that are still awaiting approval or missing information.
This gives the CFO an earlier view of future liabilities — before they appear in the accounting system — and creates a better basis for managing cash flow and budgets.
E-invoicing sends better data into the company. Wflow helps build the process that knows what to do with them.
FAQ
What Should Happen After an E-Invoice Arrives?
After receiving an e-invoice, the company still needs to determine who takes ownership of the document, who checks and approves it, and how it is passed into accounting or the ERP.
E-invoicing improves input data, but internal workflows, approval rules, exception handling and audit trails still need to be designed separately.
Is It Enough to Receive E-Invoices by Email?
Email can deliver an invoice, but it cannot manage the entire financial process.
It does not manage approval rules, detect duplicates or changed information, handle exceptions or show where an invoice has become stuck.
If e-invoicing is to create genuine value, the company needs a controlled workflow around the structured invoice.
How Does Wflow Help Process E-Invoices?
Wflow helps manage what happens after invoice receipt: one controlled entry point, document classification, data validation, rule-based approvals, exception handling, an audit trail and transfer into the accounting or ERP system.
This means an e-invoice becomes more than a new document format. It becomes part of a controlled financial process.
Why CFOs Need to Understand Peppol — Even If They Never Use It
CFOs do not need to use Peppol or understand its technical configuration. But they should understand what structured e-invoicing means for financial management: when liabilities become visible, how reliable reporting data are, how quickly approvals happen and whether e-invoicing genuinely improves the process rather than simply meeting regulatory requirements.
CFOs do not need to understand every technical detail of e-invoicing and Peppol. They do not need to know exactly how a Peppol Access Point works, how every data field is formatted or how different technical specifications for electronic documents compare.
But they do need to understand what happens to invoice data after introducing e-invoicing and Peppol — and how to turn that change into an advantage for the business.
E-invoicing represents a broader shift from invoices as documents to invoices as structured data. Peppol is one of the major infrastructures enabling the exchange of this data between businesses and systems.
>> Further reading: What Is Peppol? Why E-Invoicing Is Moving From Documents to Data
The European context matters here. Member States have different domestic e-invoicing requirements, while the EU’s ViDA reform introduces mandatory e-invoicing-based digital reporting for relevant cross-border B2B transactions from 1 July 2030. Peppol is an important European exchange network, but it is not the only permitted infrastructure across the EU.
For CFOs, e-invoicing and Peppol matter because they can change the moment when invoices become usable financial data. That affects when a company sees its liabilities, how quickly it can work with costs and how reliable its data are for decision-making.
CFOs Don't Need to Know How Peppol Works Technically
In many companies, invoices still arrive primarily as PDFs. Someone opens, reads, re-enters, forwards, approves and posts the invoice — and only then does it become part of the financial picture.
Until that point, it may be sitting in an inbox, a folder, an approval queue or simply in someone’s head.
Structured e-invoicing changes this principle. Instead of arriving only as a document intended for a person, an invoice can arrive as structured data that a system can read immediately , validate and feed into the next process.
The European e-invoicing standard EN 16931 defines a common semantic data model for core invoice information, supporting interoperability between systems.
And that is a CFO issue. Not the technical format itself, but its impact on the quality and availability of financial data.
Four Reasons Why E-Invoicing and Peppol Matter to CFOs
1. Data Quality
When an invoice arrives as structured data, the company becomes less dependent on manual re-entry.
That alone does not guarantee perfect accounting, but it creates a better starting point: more consistent information about suppliers, amounts, due dates, VAT and invoice line items.
For CFOs, data quality is fundamental. If the inputs are inaccurate, reporting will always be a more sophisticated interpretation of a flawed foundation.
Peppol can help move invoices from documents that someone has to read into data inputs that systems can process earlier and more consistently.
2. Faster Decision-Making
Financial management often suffers because even when a company has good data, those data only become visible after the fact.
Liabilities enter the financial picture only after manual processing, approval or posting. Costs become visible retrospectively. Reporting waits for the end of the process rather than showing what is happening in the business as it happens.
Structured e-invoicing can bring that moment forward.
If an invoice arrives as structured data and the company has the right workflow in place, a liability can become visible before it appears in the month-end close.
3. Cash Flow Visibility
For a CFO, an invoice is not merely an accounting document. It represents a future cash outflow.
The later an invoice enters the system, the longer the company manages cash flow using an outdated picture.
The liability already exists, but it is not visible in the right report. The supplier is waiting for payment, yet finance may not have a clear view of what has been approved, when payment is due or who is responsible.
Structured e-invoicing can improve liability visibility, but only when it is connected to invoice approvals and accounting workflows and reporting.
Otherwise, only the delivery method changes — not how the company manages its money.
4. Process Control
For CFOs, Peppol can be the starting point for much better control over what actually happens to invoices inside the business.
It becomes easier to understand who approved an invoice, where a process stalled, which documents are waiting for an exception to be resolved, which liabilities have already arisen and where risks or delays are accumulating.
Combined with Wflow, structured e-invoicing can become part of a wider control layer across the financial process.
The CFO no longer needs to wait until documents have been manually located, re-entered and posted. They can monitor the process continuously and manage finance based on what is happening now, rather than only after the month-end close.
The Biggest Risk: Delegating Peppol as a Purely Technical Project
If a company implements structured invoice reception, meets the relevant requirements but changes almost nothing internally, it misses an opportunity to make its accounting and finance operations more efficient.
Invoices still sit in queues. Approvals remain difficult to track. Cost centres are still completed manually. And CFOs continue receiving data too late, even though invoices now arrive through a more modern channel.
IT can handle the integration, but finance leadership must define the operational outcome the change is supposed to deliver.
- Will we see liabilities earlier than we do today?
- Will we reduce manual accounting work between invoice receipt and posting ?
- Will the quality of reporting data improve?
- Will invoice approvals become faster?
- Will we have a clear audit trail and accountability for financial decisions ?
- How will exceptions be handled?
These questions matter more than the technical configuration. E-invoicing creates an opportunity for CFOs to improve how their company is managed.
Want to find out whether your company treats e-invoicing as a format requirement or an opportunity to improve its financial processes?
Let’s examine your current invoice workflow and identify where structured data could deliver faster approvals, stronger control and clearer reporting.
FAQ
Why Should CFOs Care About Peppol?
CFOs do not need to understand Peppol’s technical configuration, but they should understand its impact on financial management.
Peppol can influence when invoice data become available, how quickly liabilities become visible, how reliable reporting inputs are and how much manual work remains between invoice receipt and accounting.
Is Peppol Just a Technical Topic for IT or Accountants?
IT, the accounting team or a software provider can handle the technical integration.
But the CFO should determine what the change must achieve for the business: faster approvals, better liability control, higher-quality reporting, an audit trail and less dependence on manual invoice processing.
How Is Peppol Related to E-Invoicing?
E-invoicing is the broader shift towards invoices in structured, machine-readable form.
Peppol is an infrastructure that enables the secure exchange of structured electronic documents between businesses and systems.
For CFOs, what matters most is what happens to invoice data once they reach the company.
Is Peppol Mandatory Across Europe?
No. E-invoicing requirements vary by country and transaction type. The EU’s ViDA reform introduces harmonised requirements for relevant cross-border B2B transactions from July 2030, but does not make Peppol the sole mandatory transmission network.
AI in Accounting: Routine Belongs to AI, Decision-Making Stays Human.
AI in accounting does not mean handing the entire finance function to a machine. Its greatest value lies in taking over repetitive work: classifying documents, extracting data, preparing accounting suggestions, checking routine cases and identifying exceptions. Judgement, responsibility and business context still belong with people.
AI is another layer within broader accounting automation.
Companies first digitised documents.
Then they automated workflows.
Now systems can increasingly use data from previous processing to recognise patterns and prepare better suggestions.
AI, OCR and Automation Are Not the Same Thing
These terms are often used interchangeably.
They solve different problems.
In practice, these technologies work together.
OCR can read the document.
A workflow can route it.
AI can help interpret what should happen next and whether the case looks routine or requires accountant attention.
Where Does AI Fit Into the Accounting Process?
AI creates the most value when it becomes part of an existing process rather than another isolated tool.
A connected accounting workflow may look like:
document receipt → classification → data extraction → validation → accounting suggestion → approval → ERP → archive
AI can assist at several of these stages.
That is also why introducing AI into a broken process rarely fixes the underlying problem.
If invoices still arrive in personal inboxes, approvals happen through chat and data are manually re-entered into ERP, adding an AI tool on top does not automatically create a good finance process.
The digital foundation still matters.
Read more in our complete guide to digital accounting.
What Can AI Automate in Accounting?
1. Document Collection and Classification
Documents can arrive from:
- email,
- mobile applications,
- cloud storage,
- suppliers,
- employees,
- clients of accounting firms.
A surprising amount of accounting time can be consumed before anyone actually starts accounting.
Documents have to be found, identified, sorted and assigned to the correct process.
AI can help classify incoming documents and prepare them for the right workflow.
The accountant starts where expertise is needed instead of starting with inbox administration.
2. Data Extraction and Interpretation
For a traditional invoice, the system may extract:
- supplier,
- invoice number,
- amount,
- VAT,
- issue date,
- due date,
- other accounting fields.
Modern AI processing can go beyond simply reading fixed fields.
It can combine extracted information with context and previous processing behaviour.
For the broader invoice workflow, see our guide to automated invoice processing.
3. Accounting Suggestions
This is where the difference between basic OCR and AI becomes much clearer.
An AI-supported system can consider patterns such as:
- how a supplier was accounted for previously,
- which accounts are commonly used,
- which cost centres or projects tend to apply,
- which workflow was used for similar cases,
- which previous suggestions accountants corrected.
Based on these patterns, the system can prepare a likely next step.
That does not mean:
AI has decided how the transaction must be accounted for.
It means:
the accountant does not need to start every routine case from an empty field.
4. Validation and Anomaly Detection
When the system understands typical patterns, it can become better at identifying cases that do not fit.
Examples may include:
- an unusual amount,
- missing information,
- duplicate documents,
- an unexpected bank-account change,
- an unusual accounting treatment,
- a new type of transaction.
This changes the way control works.
Accountants do not need to give every document exactly the same level of attention.
Their attention can shift towards exceptions.
5. Identifying Where Human Attention Is Needed
One of the most valuable uses of AI may not be making a decision.
It may be deciding:
This case looks routine. This one does not.
That creates a process where standard cases can move faster while human attention is concentrated on ambiguity, risk and exceptions.
What Should AI Not Automate in Accounting?
Not everything that a system can suggest should become an autonomous decision.
Accounting decisions can have:
- tax consequences,
- legal consequences,
- financial consequences,
- reporting consequences,
- company-specific context.
AI can prepare information and suggestions.
People still need to know:
- when to trust the suggestion,
- when to verify it,
- when to modify it,
- when to stop the process entirely.
We explore this boundary in more detail in AI in Accounting and Responsibility for Errors.
Human in the Loop: Why People Remain Part of AI Accounting
Human oversight does not mean that someone needs to manually verify every action.
It means the system should be able to distinguish when human review is required.
A practical model can contain three levels.
High Confidence
The case matches established patterns and company rules.
The process can continue automatically or with minimal intervention.
Medium Confidence
The system prepares a suggestion but requires quick confirmation.
Low Confidence or Exception
Something does not fit.
The process stops and the accounting team reviews the case.
This is more useful than either extreme:
“AI cannot do anything without approval.”
or:
“AI should process everything by itself.”
The goal is to place human attention where it creates the most value.
How Does AI Change Invoice Processing?
Invoices are one of the most natural starting points for AI in accounting.
The process includes many repetitive stages:
- receiving the document,
- classification,
- data extraction,
- validation,
- approval,
- preparation of accounting information,
- transfer into ERP.
Traditional automation can already manage many of these stages using rules.
AI adds another layer.
It can help:
- interpret the document,
- recognise previous patterns,
- prepare accounting suggestions,
- identify anomalies,
- determine whether human review is necessary.
AI therefore changes automation in two ways.
It can reduce the number of manual steps.
And it can reduce the amount of automation logic that teams need to configure manually.
What Changes When E-Invoicing Becomes Structured Data?
Structured e-invoicing removes one important task from the traditional document workflow:
reading basic invoice information from a visual document.
When an invoice arrives as structured data, the system does not need OCR to discover basic fields such as invoice number or amount.
Those data already exist in machine-readable form.
That does not make AI irrelevant.
Its value simply moves further into the process.
AI can focus more on:
- interpretation,
- accounting suggestions,
- validation,
- anomaly detection,
- company history,
- deciding which cases need human attention.
Across Europe, this distinction becomes more important as structured e-invoicing expands and finance systems exchange more machine-readable data directly.
Read more in What Is Peppol? How E-Invoicing Is Moving Europe from Documents to Data.
What Are the Main Benefits of AI in Accounting?
Less Manual Work
Accountants do not need to repeat the same administrative actions for every document.
Less Manual Rule Maintenance
Traditional automation depends heavily on rules created and maintained by people.
AI can help identify recurring patterns and prepare suggestions based on real processing behaviour.
More Targeted Control
Instead of applying the same review effort to every document, finance can focus more attention on exceptions and uncertainty.
Greater Team Capacity
If routine administration does not grow at the same pace as document volume, accounting teams can process more work without administrative capacity increasing proportionally.
More Time for Higher-Value Work
Accountants can spend more time on:
- exceptions,
- control,
- closing,
- data quality,
- advisory,
- client communication,
- financial interpretation.
What Are the Risks of AI in Accounting?
Automating a Bad Process
If the underlying workflow is unclear, AI can simply make a poor process move faster.
Overconfidence in AI Suggestions
A suggestion can look convincing and still be wrong.
The system therefore needs clear rules around when a suggestion can continue and when it requires review.
Poor Traceability
Finance teams need to understand what the system suggested and what a person subsequently confirmed or changed.
Missing Local Accounting Context
There is no single accounting or tax practice that applies identically across every European country.
National VAT rules, reporting obligations and accounting practice still matter.
AI therefore needs to operate within the relevant accounting environment rather than assuming that the logical structure of an invoice is enough.
Automating Responsibility
The biggest mistake is treating an AI suggestion as if it were automatically an accountable professional decision.
It is not.
AI can be a powerful working tool.
Responsibility for how its output is used still needs to be clearly defined.
How to Introduce AI Into Accounting
1. Start With the Process, Not the AI Tool
Map what happens to a document today.
Where does repetitive work occur?
Where does the process wait?
Where are data re-entered?
Where is context lost?
2. Choose a Repetitive Process
AI creates the most value where there are enough recurring cases and patterns to work with.
Invoice and document processing is often a practical starting point.
3. Separate Routine From Judgement
Define:
- what the system may do automatically,
- what it may only suggest,
- what always requires human confirmation.
4. Define Exceptions
Do not focus only on when automation should continue.
Define clearly when it must stop.
5. Preserve Traceability
It should be possible to determine:
- what the system suggested,
- what a person approved,
- what they changed,
- when those actions occurred.
6. Connect AI With the Accounting or ERP Environment
AI should not become another isolated data silo.
It should operate as part of the existing finance process.
7. Measure the Result
Useful metrics may include:
- number of manual interventions,
- document-processing time,
- percentage of cases requiring review,
- number of exceptions,
- accountant time spent on routine work,
- time spent correcting suggestions.
The objective is not to have more AI.
The objective is to have less unnecessary work and stronger control.
How Will AI Change the Role of Accountants?
The biggest change is unlikely to be the disappearance of accountants.
It will be a change in the mix of work.
As systems take over more routine activity, the value of work requiring these skills increases:
- professional judgement,
- interpretation,
- exception handling,
- communication,
- control,
- advisory.
For accounting firms, that can mean serving more clients without every new client creating the same increase in manual administration.
For internal finance teams, it can mean more capacity for control, closing, analysis and financial management.
Accounting routine belongs to AI.
Decision-making stays human.
How Wflow Accounting Autopilot Fits Into This Model
Wflow Accounting Autopilot is an AI layer above the existing accounting process.
It is designed to automate routine document work such as:
- collecting and classifying incoming documents,
- extracting relevant information,
- preparing accounting suggestions,
- identifying inconsistencies,
- showing which cases need accountant attention,
- preparing information for the accounting or ERP system.
Wflow does not replace the accounting system.
It works as a layer above the existing accounting or ERP environment.
The principle remains the same:
AI handles routine work. People decide where responsibility, experience and context are required.
Want to Find Out Which Part of Your Accounting Routine AI Could Take Over?
You do not need to redesign your entire finance function at once.
Start with the tasks accountants repeat every day and separate the work that genuinely requires professional judgement from the work a system can prepare automatically.
FAQ
What Is AI in Accounting?
AI in accounting uses artificial intelligence to process documents and financial data, recognise patterns, prepare accounting suggestions, identify anomalies and automate repetitive work.
What Is the Difference Between AI and Accounting Automation?
Traditional automation usually performs predefined actions based on explicit rules.
AI can also use historical data, context and recurring patterns to prepare suggestions or identify unusual cases.
In practice, the two technologies work together.
What Is the Difference Between OCR and AI?
OCR primarily identifies text and fields in a document.
AI can then use those data together with context and historical behaviour to prepare suggestions about what should happen next.
What Can AI Automate in Accounting?
AI can support document collection and classification, data extraction, accounting suggestions, validation, anomaly detection and identification of cases requiring human attention.
Will AI Replace Accountants?
No.
AI is best suited to repetitive and predictable work.
Professional judgement, responsibility, interpretation, exception handling and advisory remain human responsibilities.
Can AI Post Accounting Entries Automatically?
For sufficiently standard cases, AI-supported systems can automate a large part of the preparation and processing workflow.
That does not mean professional responsibility should automatically be transferred to AI.
Companies still need clear rules around which cases may continue automatically and which require review.
Is AI in Accounting Safe?
Safety depends on implementation.
Human oversight, traceability, exception handling, access controls and a well-designed underlying accounting process are essential.
When Does AI Create the Most Value in Accounting?
AI creates the greatest value where accounting teams process large volumes of similar cases, repeatedly enter the same information, maintain many recurring rules or spend excessive time reviewing routine documents.
How Does AI Relate to E-Invoicing?
Structured e-invoicing reduces the need to extract basic information from visual invoices.
AI can therefore focus more on later stages such as interpretation, accounting suggestions, validation and exception handling.
What Is Wflow Accounting Autopilot?
Wflow Accounting Autopilot is an AI layer designed to automate routine document processing.
It classifies documents, extracts information, prepares accounting suggestions, identifies inconsistencies and shows where accountant attention is required.
Text updated in November 2026
What Is the Difference Between UBL, XML, a Structured E-Invoice and Peppol?
XML, UBL, structured e-invoices and Peppol are often mentioned in the same conversation about e-invoicing, but they do not mean the same thing. XML is a technical way of representing data, UBL is a standardised XML-based syntax used for business documents, a structured invoice is the principle of working with machine-readable invoice data, and Peppol is an infrastructure for securely exchanging that data between systems.
At first glance, they may sound like different names for the same thing. In reality, they describe different layers of the same ecosystem.
- XML is a technical language in which data can be written.
- UBL is a standardised XML-based syntax used for electronic business documents, including invoices.
- A structured invoice is an invoice in a machine-readable format, for example using UBL or another standardised data syntax. An e-invoice is an invoice that is issued, transmitted and processed between systems in this structured form.
- Peppol is an infrastructure through which companies can securely exchange structured electronic documents.
The European standard EN 16931 defines the common semantic data model for the core elements of an electronic invoice. The European Commission lists UBL 2.1 and UN/CEFACT CII among the syntax bindings used to implement it.
XML Is Not an Invoice. It Is a Way of Representing Data
Not to be confused with .xlsx, the file format commonly used for Excel spreadsheets.
XML is a technical way of representing data so that software can understand it.
You can store invoice information in XML, but you can also use XML for purchase orders, warehouse data or completely different types of documents.
XML itself therefore does not know that something is an invoice.
It simply means that the data are represented in a structured form.
For XML data to function as an e-invoice, they need specific rules defining which information must be included, where it belongs and how accounting systems should interpret it.
This is where standards and specifications such as EN 16931, UBL and Peppol BIS come into play.
UBL Is a Standardised Syntax for Electronic Business Documents
UBL, or Universal Business Language, is a standardised XML-based syntax for electronic business documents, including invoices, orders and credit notes.
In European e-invoicing, UBL is particularly relevant because it is one of the syntaxes used to represent invoices conforming to the European standard EN 16931. Peppol BIS Billing also uses UBL for structured invoice exchange.
You can think of it as one of the bridges between invoice information and a world in which accounting systems exchange structured data automatically.
Different countries and markets may also use their own implementations or formats, for example:
- XRechnung in Germany
- ZUGFeRD / Factur-X in Germany and France
- FatturaPA in Italy
The important point is that these formats are not simply different kinds of PDFs. They define how invoice data are structured so that software can interpret them.
A Structured Invoice Is an Invoice a System Can Work With
A structured invoice is not simply a document stored digitally.
A PDF invoice, for example, may be digital. But if a system cannot read its contents without OCR or manual data entry, it still primarily functions as a document designed for a person.
A structured invoice contains data in a format that software can use directly: it can read the information, validate it, pre-fill accounting data, send the invoice for approval or connect it with an ERP system.
This is where the real difference between digitising a document and automating a process begins.
Peppol Is Not an Invoice Format. It Is a Network for Exchanging Documents
Peppol is often confused with an invoice format.
More precisely, it is an infrastructure and a set of specifications for securely exchanging electronic documents between companies, public-sector organisations and systems.
It can be used to exchange documents such as e-invoices, orders and other structured business documents.
Why This Distinction Matters for Finance Teams
Companies often focus on whether they will need a new format, a new integration or a new system.
But the biggest question is not purely technical.
What matters is what happens to the invoice after it reaches the company.
If a structured invoice enters a process where people still manually approve it, copy information between systems, search through emails and perform the same checks by hand, much of its value is lost.
E-invoicing creates the greatest value when it is connected with accounting automation, invoice approval, audit trails, ERP integration and a well-designed finance workflow.
Where Wflow Fits In
Wflow helps companies use structured data so that e-invoicing becomes more than simply a new way of delivering a document.
In Wflow, an invoice can continue directly into approval, accounting context, validation, archiving, the audit trail and transfer to the ERP system.
That is the important distinction.
The future of accounting will not depend only on whether a company uses XML, UBL or Peppol.
It will depend on whether it can work with invoice data as part of a process rather than treating each invoice as another file.
FAQ
Is XML the Same as an E-Invoice?
No. XML is a technical language for representing data.
An e-invoice can use XML, but XML itself does not define a particular invoicing standard.
What Is UBL?
UBL, or Universal Business Language, is a standardised XML-based syntax for electronic business documents.
It is one of the syntaxes used in European e-invoicing and can be used to represent structured invoice data.
What Is a Structured Invoice?
A structured invoice is an invoice in a machine-readable form.
A system can read its data and continue processing them without manually re-entering the information.
Is Peppol an Invoice Format?
No. Peppol itself is not an invoice format.
It is an infrastructure and set of specifications for securely exchanging electronic documents between systems.
How Are UBL and Peppol Related?
UBL is a syntax used to structure electronic business data.
Peppol is an infrastructure for exchanging structured electronic documents. Peppol BIS uses standardised document specifications, including UBL-based invoice messages.
Why Is Having a Structured Invoice Format Not Enough?
Because the format only defines the data.
A company still needs a process for approvals, validation, audit trails, accounting and ERP integration.
Sources:
- European Commission – e-Invoicing
- OpenPeppol – About Peppol
- W3C – XML standard
What is Automated Bookkeeping? The Ultimate Guide for Modern CFOs
Accounting automation is about more than extracting data from invoices faster. The real value appears when document intake, validation, approvals, accounting context, ERP integration, archiving and reporting work as one connected process.
Accounting automation is not the same as digitalization. Digital accounting creates the digital data and connected environment. Automation then allows repetitive parts of that process to run according to rules with fewer unnecessary manual interventions.
The term automated bookkeeping is also commonly used, particularly for automation around document processing and bookkeeping tasks. Accounting automation is the broader concept: it can cover the entire process from document receipt to ERP integration, control and financial reporting.
In this guide, you will learn:
- what accounting automation means,
- how automated bookkeeping works in practice,
- which accounting processes can be automated,
- where automation creates the greatest value,
- how AI changes accounting automation,
- how to implement automation step by step,
- how to calculate its return on investment.
How Does Accounting Automation Work?
A connected accounting automation process can include the following stages.
1. Document and Data Collection
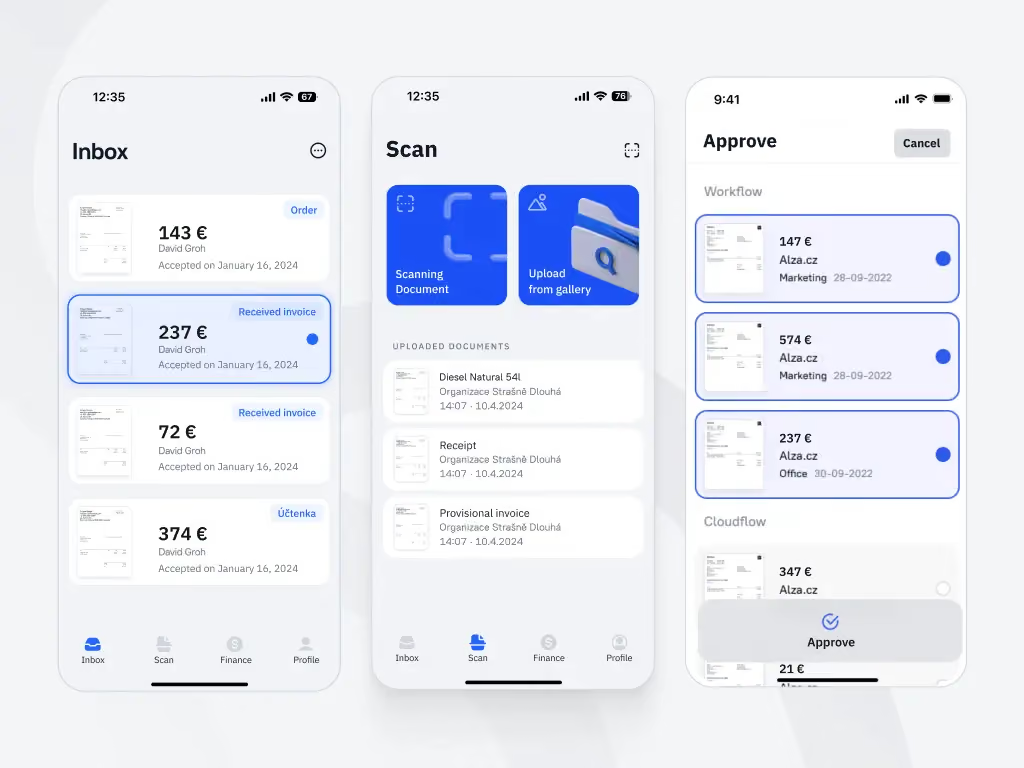
Invoices, receipts, orders and other accounting documents enter the system through controlled channels such as email, upload, mobile app, API or structured e-invoicing.
The aim is to prevent documents from remaining scattered across inboxes, folders and individual employees.
2. Automated Data Extraction and Validation
OCR and AI extract the information needed for further processing, such as supplier, invoice number, VAT data, amounts and due dates.
Modern automated invoice processing goes beyond reading a document. The system can validate information, compare it with other data and prepare the invoice for the next stage.
3. Approvals and Exception Handling
Documents are routed according to company rules — for example by amount, supplier, department, project or cost centre.
Routine cases can move through the process quickly. Exceptions should stop and be sent to the person who has the context and authority to decide what happens next.
4. Preparation for Accounting and ERP Transfer
Once the document has been checked and approved, the system prepares structured accounting data and passes them into the accounting or ERP environment according to the company’s setup.
Automation does not mean that every transaction must be posted without human oversight.
Non-standard or uncertain cases can remain subject to accountant review.
5. Archiving and Auditability
Documents need to remain accessible after processing, together with the context of what happened to them.
6. Reporting and Financial Management
Automation should not end when information reaches the accounting system.
The faster complete and validated data move through the process, the earlier finance can use them for reporting, planning and decision-making.
What Accounting Processes Can Be Automated?
Automation works best for repetitive activities with clearly defined rules and sufficiently reliable input data.
Typical examples include:
- document and invoice collection,
- invoice data extraction and automated invoice processing,
- validation of required information,
- matching documents with purchase orders or transactions,
- invoice and expense approvals,
- routing and recurring exception handling,
- preparation of accounting suggestions,
- transfer of data into accounting or ERP systems,
- digital archiving,
- audit trails,
- expense management,
- reporting and budget workflows.
AI adds another layer to this process. It can recognise recurring accounting patterns and prepare suggestions, but automation still needs a clear boundary between routine work and accountable decisions.
We explain that boundary in AI in Accounting and Responsibility for Errors.
The Main Benefits of Accounting Automation
Less Manual Data Entry
When information is captured once and reused throughout the process, finance teams spend less time copying the same data between emails, spreadsheets, approval tools and accounting systems.
Fewer Routine Errors
Automation can reduce errors caused by repeated manual entry and help maintain more consistent processing.
It does not eliminate errors completely. Reliable automation still depends on good input data, validation, sensible rules and proper handling of exceptions.
Faster Document Processing
Documents do not have to wait for someone to manually classify them or forward them to the next person in the process.
Better Process Visibility
Finance teams can more easily see where a document is, whether it has been approved, which exceptions exist and what needs human attention.
Greater Scalability
When a higher volume of documents does not create the same increase in repetitive administrative work, finance teams can support company growth more efficiently.
More Time for Higher-Value Finance Work
The purpose of automation is not simply to process documents faster.
It is to shift finance capacity away from repetitive administration and towards control, exceptions, analysis and decisions.
What Should Accounting Automation Software Be Able to Do?
Manage the Entire Document Lifecycle
Automation should not end after extracting fields from an invoice.
A suitable platform should support the process from document intake and validation through approval and preparation for accounting to archiving and traceability.
Support Configurable Rules
Every company has different approval structures, accounting practices and responsibilities.
Automation therefore needs to work with rules based on attributes such as amount, supplier, project, document type, cost centre or user role.
Handle Exceptions Properly
Good automation is not about forcing every case through without a person.
Routine cases should move faster, while uncertain or unusual situations should be clearly identified and routed for review.
Connect With Existing Accounting and ERP Systems
Automation should not create another isolated data silo.
A suitable platform needs to exchange structured information with the accounting or ERP environment already used by the company.
Wflow can connect to existing accounting and ERP systems through ready-made integrations or an open API, so companies do not necessarily need to replace their accounting backbone when automating the processes around it.
Maintain Traceability
Important actions need to remain auditable.
Finance should be able to see what happened to a document, who worked with it and where human decisions were made.
Support Secure Digital Archiving
Documents need to remain accessible and retrievable after processing.
How to Implement Accounting Automation Step by Step
Accounting automation does not need to be introduced as one large transformation project.
A better approach is usually to start with the process where repetitive manual work creates the greatest cost or delay.
1. Map the Current Process
Document how accounting information actually moves through the company.
Where does an invoice arrive? Who checks it? Who approves it? Where are data manually entered again? Where does the process wait?
Do not map only the accounting team. Purchasing, employees, managers, approvers and finance leadership may all be involved.
2. Find the Most Expensive Manual Step
You do not need to automate everything at once.
Look for activities with a high volume of repetitive work and clear rules.
These are usually the best candidates for early automation.
3. Separate the Rule From the Exception
A routine case can often continue automatically.
An exception should be routed to a person with the context and authority to make the decision.
This distinction matters more than trying to maximise the percentage of cases that run without human involvement.
4. Define Responsibilities and Approval Logic
Decide who is responsible for each step and what determines where a document goes next.
5. Choose a Solution That Connects to the Existing Accounting Environment
Automation should not force a company to replace a working ERP simply to improve the process around it.
The automation layer should connect document processing, validation, approvals and controls with the accounting environment already in use.
6. Start With a Pilot
Accounts payable is often a practical starting point.
It has a clear beginning and end, relatively repetitive workflows and measurable manual effort.
7. Measure the Result
Useful metrics can include:
- processing time per document,
- number of manual interventions,
- approval time,
- number of exceptions,
- number of missing documents,
- time from receipt to transfer into accounting,
- time until information becomes available for financial management.
Without measurement, automation can easily turn into another software implementation project rather than a genuine process improvement.
When Does Accounting Automation Create the Most Value?
Automation is particularly useful when:
- document volumes are increasing,
- several people repeatedly approve similar expenses,
- accountants re-enter information between systems,
- documents are regularly missing before close,
- teams spend large amounts of time on recurring exceptions,
- the ERP works well but the process before it remains manual,
- business growth automatically creates more finance administration.
The strongest automation candidates are usually processes where the same routine activity happens frequently and follows relatively predictable rules.
Will Accounting Automation Replace Accountants?
No.
Automation creates the most value when it takes over routine work, not professional responsibility.
Accountants can spend less time sorting documents, copying data and checking standard cases, and more time on exceptions, control and professional judgement.
AI pushes this transition further.
Wflow Accounting Autopilot is being developed as an AI layer above the existing accounting process. It is designed to automate more of the routine document journey while showing where accountant attention is required.
The objective is therefore not to automate responsibility.
It is to automate routine work.
For a broader view of that shift, see AI in Accounting: What It Will Automate and What Stays Human.
How Does E-Invoicing Change Accounting Automation?
Structured e-invoicing changes the way invoice data enter the finance process.
Instead of extracting information from a visual document such as a PDF, systems can increasingly receive invoice information as structured data.
That improves the input.
It does not automatically solve what happens afterwards.
The company still needs:
- validation,
- approval,
- exception handling,
- accounting context,
- transfer into ERP,
- archiving and traceability.
This is particularly important across the EU, where e-invoicing requirements are developing at different speeds in individual Member States, while EU rules are also moving towards more structured and machine-readable financial data.
For a practical explanation, see E-Invoicing and Invoice Workflow: What Happens After Receipt.
You can also read our broader guide to Peppol and e-invoicing in Europe.
How Do You Calculate the ROI of Accounting Automation?
Start by calculating how much time the company currently spends on manual document processing, approvals, matching, searching for information and correcting avoidable errors.
Convert that time into a financial cost and compare it with the cost of software, implementation, integrations and internal implementation effort.
A simple formula is:
ROI = (annual savings − annual automation costs) / annual automation costs × 100
For a more useful calculation, measure:
- time spent processing one document,
- number of manual interventions,
- approval time,
- number of exceptions,
- avoidable correction work,
- software and implementation costs.
The most common mistake is to compare only licence prices.
The real value of automation depends on how much repetitive work, waiting and process friction it removes.
Want to Find Out Where Accounting Automation Would Create the Most Value?
You do not need to automate your entire finance function at once.
Start with the process where repetitive manual work creates the most friction and use it to test what automation can realistically remove.
FAQ
What Is Accounting Automation?
Accounting automation is the use of software to take over repetitive stages of accounting processes, such as document collection, data extraction, validation, routing, approvals and preparation of structured data for accounting or ERP systems.
Its purpose is not to replace accounting software or accountants, but to reduce unnecessary manual work across the process.
What Is the Difference Between Automated Bookkeeping and Accounting Automation?
Automated bookkeeping usually refers to the automation of routine bookkeeping activities such as data entry, document processing and preparation for posting.
Accounting automation is the broader concept. It can include approvals, exception handling, ERP integration, auditability, archiving and the flow of financial information beyond bookkeeping itself.
Is Automated Accounting Accurate?
Automation can reduce errors caused by repeated manual data entry.
Accuracy still depends on the quality of input data, system configuration, validation rules and proper handling of exceptions.
Modern automation therefore combines automated processing with human review where professional judgement is required.
Will Accounting Automation Replace Accountants?
No.
Automation is best suited to repetitive and rule-based activities. Professional judgement, responsibility, interpretation of exceptions and more complex decisions remain with the accounting team.
Do We Need to Replace Our ERP to Automate Accounting?
Not necessarily.
Modern automation platforms can operate as a process layer around the existing accounting or ERP system and pass prepared, validated data into it.
How Do You Measure the ROI of Accounting Automation?
Compare annual savings from reduced manual work and process costs with the annual cost of software, implementation and integrations.
Measure the whole process rather than comparing licence prices alone.
Sources
- Deloitte report 2026: State of AI in the Enterprise - The untapped edge
- KPMG: Digitalisation in accounting 2025/2026: These are the most important trends at a glance
- European Commission: VAT in the Digital Age
- European Commission: Electronic Invoicing
Text updated: November 2026
A Complete Guide to Automated Invoice Processing: Invoice Data Extraction Without Manual Work
By introducing automated invoice processing, you free your finance team from manual work and allow them to focus on the company’s future and financial health. This guide explains how invoice automation software works in practice, what specific benefits it delivers and how to implement it without unnecessary complications.
Manually re-entering invoice data is not only outdated, but also costly and inefficient. Automated invoice processing saves time, reduces errors and accelerates payments. This guide explains how invoice automation software improves cash flow and financial operations—and why it is becoming essential for modern finance teams.
- What invoice automation is and how it works
- The main benefits of automated invoice processing
- Essential features of modern invoice automation tools
- How to implement automated invoice processing
- Requirements for different types of businesses
- Common obstacles and how to overcome them
What Is Invoice Automation?
Definition and Core Technology
Invoice automation means using software to process incoming and outgoing invoices automatically—from receiving the document and extracting its data to approval and posting.
The objective is to eliminate manual data entry and connect the individual stages of invoice processing into one controlled digital workflow.
How Automated Invoice Processing Works
Invoice automation software typically uses:
- OCR (optical character recognition) to read invoices and accounting documents.
- AI (artificial intelligence) to extract and automatically validate invoice data.
The system identifies key information, compares it with purchase orders and prepares the document for approval.
Automated Invoice Processing vs. Manual Processing
Benefits of Invoice Automation Software
Elimination of Manual Data Entry
Automated invoice processing significantly reduces the volume of manual work and data entry. This also lowers the administrative costs of finance and accounting teams.
Fewer Errors and Fraudulent Invoices
Automated data validation and approval workflows minimise the risk of errors, duplicate invoices and fraudulent documents.
Faster Payments and Better Cash Flow
Automation makes it possible to approve invoices within minutes. This shortens payment cycles and improves relationships with suppliers.
Better Visibility and Real-Time Reporting
Finance teams can see the status of every invoice in real time, making expense planning and financial control significantly easier.
Key Features of Modern Invoice Automation Software
AI-Powered Invoice Data Extraction
Modern software can automatically recognise and extract information from different invoice and document formats without requiring manual data entry.
Three-Way Matching
An accounting digitalisation platform such as Wflow automatically compares data from the invoice, purchase order and goods receipt.
When the system identifies a discrepancy, it flags it immediately for review.
Automated Approval Workflows
Flexible approval rules and notifications can be configured for different roles and responsibilities. Invoices can be approved in real time, including through a mobile application.
ERP and Accounting Software Integration
Integration with accounting software, ERP platforms and other business systems eliminates repeated data entry and reduces the risk of errors.
Companies can modernise invoice processing without replacing the accounting or ERP systems they already use.
Exception Alerts and Notifications
Reliable invoice automation software automatically alerts users to errors, discrepancies and missing information.
How to Get Started With Automated Invoice Extraction and Processing
Assess Invoice Volume and Process Weaknesses
Map your current process:
- How many invoices pass through your company each month?
- Where do the biggest approval delays occur?
- At which stage do errors most often appear?
Understanding the current workflow helps identify where automation can create the greatest value.
Choose the Right Platform
Compare available solutions based on:
- features,
- integrations,
- implementation requirements,
- and vendor support.
The right platform should fit your existing finance environment rather than force the company to rebuild it.
Configure Workflows and Rules
Define approval processes and set automation rules according to your organisation’s structure.
This may include:
- approval limits,
- role-based permissions,
- escalation rules,
- cost centres,
- and specific workflows for different document types.
Train Teams and Suppliers
Explain the new process clearly to internal users and external partners.
Successful implementation depends not only on the software itself, but also on whether people understand how documents should enter and move through the new workflow.
Measure the Benefits
Regularly evaluate:
- time savings,
- faster approvals,
- fewer errors,
- and shorter payment cycles.
Process configuration is largely a one-time investment, while the efficiency gains continue to grow over time.
How Automated Invoice Processing Works in Different Types of Businesses
Solutions for Small and Medium-Sized Businesses
Companies with fewer employees usually prefer tools that are easy to implement and affordable in terms of both time and cost.
A key requirement is integration with the accounting or ERP system the company already uses.
This allows SMEs to automate invoice processing without replacing a familiar and proven financial system.
Enterprise Solutions
More complex organisations require advanced workflows and greater process customisation.
Automated invoice processing can save dozens of hours each month and provide full control over financial operations.
Processes become faster, while finance teams can focus on more complex tasks that directly contribute to a financially healthier company.
Industry-Specific Requirements
Retail, manufacturing, professional services and accounting firms all have different requirements for:
- approvals,
- reporting,
- integrations,
- and document handling.
Wflow is used by companies across all of these industries.
Explore our customer case studies.
Common Obstacles to Efficient Finance Workflows
Inconsistent Invoice Formats
Working with different invoice and document formats takes time—and sometimes strong glasses.
Modern OCR technology can process different templates and non-standard documents without difficulty.
Delayed Supplier Payments
A heavy workload in the accounting team often leads to payment delays.
Invoice automation software helps prevent these delays by moving documents through validation and approval more efficiently.
It is worth communicating the benefits of automation to suppliers as well.
Faster payments and fewer errors can become a competitive advantage in supplier relationships.
Integration With Legacy Systems
Look for a solution with an open API and proven experience in system integration and data migration.
Wflow integrates with a wide range of established accounting and ERP systems, helping companies introduce a new workflow without unnecessary disruption.
FAQ
What Is Invoice Automation?
Invoice automation is the process of using software to handle incoming and outgoing invoices without manual data entry.
How Does Invoice Automation Software Work?
It uses OCR, AI and automated workflows to extract, validate and approve invoice data.
How Much Does Automated Invoice Processing Cost?
Pricing depends on invoice volume, required features and the licensing model. Most solutions are offered as a monthly subscription.
Can Invoice Automation Be Integrated With Our ERP?
Yes. Most modern invoice automation platforms integrate with ERP and accounting software.
What ROI Can We Expect From Invoice Automation?
The return depends on your invoice volume, current processing costs and the amount of manual work involved.
Contact the Wflow team to calculate the potential ROI based on your actual data. According to Stripe, automation costs can represent roughly one-third of the cost of manual processing. (Source: Stripe.com)
Sources
- J. P. Morgan: What is accounts payable automation?
- Stampli.com: 50+ accounts payable statistics about AI, automation, & more
- Parseur.com: Global Trends In AI Invoice Processing - Adoption Rates, Costs, And Challenges
- Deloitte : E-Invoicing: A catalyst for finance transformation and compliance

Expense Management: How to Get Business Spending Under Control
Expense management does not begin when finance receives a receipt or invoice. An expense starts when someone decides that the company needs to buy something, and it ends only when that cost has been approved, documented, accounted for and made visible in financial data.
Expense management is one part of the broader digital accounting architecture.
It is therefore much broader than receipt scanning, travel expenses or employee reimbursements.
Expense management can include:
- purchase requests,
- budget checks,
- approval rules,
- purchasing and payments,
- invoices and receipts,
- matching documents with transactions,
- accounting and ERP integration,
- auditability,
- reporting and spend control.
The objective is not to add more administration.
It is to prevent finance teams from spending the end of every month chasing receipts, re-entering data and trying to reconstruct who approved what.
The Problem Usually Exists Between the Tools
A company may already use:
- digital invoices,
- corporate cards,
- online banking,
- an ERP,
- approval tools,
- spreadsheets,
- accounting software.
And still have poor control over spending.
Why?
Because digitising individual activities is not the same as creating a connected process.
An expense may be approved in a chat, paid with a card, documented by email, entered into a spreadsheet and then manually transferred into accounting.
Every individual step is digital.
The process between them is still manual.
That is where context disappears, delays appear and finance teams end up rebuilding information afterwards.
Where Do Companies Lose Control of Expenses?
Expense-management problems usually appear at several points in the lifecycle.
Before the Purchase: Finance Does Not Know the Expense Is Coming
A team needs another software licence.
Marketing orders a service.
An employee purchases equipment.
If the company has no structured purchase process, finance may not learn about the expense until the invoice arrives.
At that point, it is too late to decide whether the purchase should have happened.
Typical problems include:
- unclear purchasing authority,
- budgets checked only after spending,
- approval through email or chat,
- no visibility into commitments,
- purchase orders created too late or not at all.
Good expense management therefore starts before the invoice exists.
At the Point of Payment: The Transaction Exists, the Context Does Not
Another gap appears when a payment is made.
An employee pays by corporate card or personal card and continues with their day.
Weeks later, finance sees a transaction but may not know:
- what it was for,
- who made it,
- which department or project owns it,
- where the receipt is,
- whether the purchase was approved.
A bank or card transaction tells accounting very little by itself.
Its value comes from the context attached to it.
After the Purchase: Finance Starts Chasing Information
If the previous stages are disconnected, the administrative work moves downstream.
Finance then deals with:
- missing receipts,
- manual data entry,
- expense reports,
- reimbursement requests,
- approval by email,
- manual transaction matching,
- repeated questions about individual payments.
The consequence is not only more work.
The company also receives reliable cost information later than management needs it.
What Does the Complete Expense Management Process Look Like?
Modern expense management connects the entire journey:
Need → Budget → Approval → Purchase or Payment → Document → Validation → Accounting → Reporting
1. A Need Arises
Someone wants to buy software, equipment, services, travel or materials.
Important financial context already exists at this point:
- who is requesting the purchase,
- what it is for,
- which team or project needs it,
- approximately how much it will cost.
2. Budget Context Is Checked
Approval should not happen without knowing whether the relevant team, project or cost category still has sufficient budget.
Budget information therefore needs to become part of the decision rather than merely a retrospective report.
3. The Expense Is Approved
Not every expense needs to follow the same workflow.
Rules can depend on factors such as:
- amount,
- department,
- project,
- expense category,
- cost centre,
- type of purchase.
The important point is that employees know who decides and finance can later see who approved the expense and under which rules.
4. The Purchase or Payment Takes Place
Depending on the type of expense, the company may use:
- an invoice,
- bank transfer,
- corporate card,
- virtual card,
- personal card with reimbursement,
- another authorised payment method.
The payment method itself is only one part of expense management.
5. The Supporting Document Is Captured
The invoice or receipt should enter the process as close as possible to the moment the expense occurs.
The longer the delay between payment and documentation, the greater the chance that finance will need to chase the document later.
6. The Expense Is Validated and Matched
Software can help:
- extract information from the document,
- match the document with a transaction,
- validate required fields,
- categorise the expense,
- route it to the correct person,
- identify exceptions.
Automation removes repetitive work while preserving company controls.
7. Data Move Into Accounting or ERP
Once approved, information should not need to be typed again by the accounting team.
Document data, transaction context, approvals and accounting information can continue into the existing accounting or ERP system.
This is where expense management connects directly with broader accounting automation.
8. The Expense Becomes Financial Information
Only then does an operational purchase become useful management information.
Finance can start monitoring:
- actual spending,
- commitments,
- team or project costs,
- deviations from plans,
- exceptions requiring attention.
Where Do Corporate Cards Fit Into Expense Management?
A corporate card is not an expense-management system.
It is a payment method.
Its value increases when the transaction is connected with:
- the employee,
- spending rules or limits,
- the receipt,
- the purpose of the expense,
- approval context,
- accounting data.
A connected process might look like this:
- An employee pays with a corporate card.
- The transaction enters the system.
- The employee attaches or photographs the receipt.
- The document is matched to the transaction.
- Required context is added.
- The expense passes through validation or approval.
- Structured data continue into accounting or ERP.
The real improvement is therefore not the card itself.
It is the removal of the information gap between payment and accounting context.
What Can Be Automated in Expense Management?
Expense-management automation does not mean that software independently decides what a company is allowed to buy.
The objective is to automate repetitive work where rules are sufficiently clear.
Typical candidates include:
- collecting receipts and invoices,
- extracting data from documents,
- matching documents with transactions,
- checking required information,
- categorising expenses,
- routing expenses to the correct approver,
- reminding users about missing documentation,
- validating expenses against defined rules,
- preparing accounting suggestions,
- passing approved data into accounting or ERP.
AI can extend this further.
It can help classify documents, recognise recurring patterns, suggest accounting treatment and highlight anomalies.
But automation of data processing is not the same as automation of responsibility.
For more on that distinction, see AI in Accounting and Responsibility for Errors.
Wflow’s Accounting Autopilot is built around the same principle: routine document work can increasingly be automated while exceptions and accountable decisions remain visible to the accounting team.
Expense Control Is About More Than Saving Time
Faster receipt processing is useful.
From a CFO perspective, however, speed is not the main objective.
Control is.
A company should be able to answer questions such as:
- Who initiated this expense?
- Who approved it?
- Under which rule?
- Which budget does it belong to?
- Which document supports it?
- Was anything changed?
- How did the information reach accounting?
Digital tools cannot prevent every mistake or misuse.
But clear responsibilities, approval rules, traceable decisions and complete documentation create a much stronger control environment than retrospective reconstruction.
What Should Expense Management Software Be Able to Do?
There is no universal feature checklist that fits every organisation.
The more useful question is whether the software can support the company’s real expense process.
A suitable system should typically be able to:
- support configurable approval rules,
- capture invoices and receipts digitally,
- extract document data,
- match documents with transactions,
- handle different expense and payment types,
- retain traceable process history,
- connect with accounting or ERP systems,
- work efficiently for employees as well as finance,
- provide structured data for further financial management.
Wflow connects document processing, approvals and the existing accounting or ERP environment through ready-made integrations and an open API.
The key question when evaluating software is therefore not:
How many features does the platform have?
It is:
Does the platform connect the whole process, or does it digitise only one step?
How to Implement Expense Management
Do not begin by buying software and then deciding which process to put into it.
Start with the process.
1. Map How an Expense Currently Moves Through the Company
Follow one real expense from the moment someone wants to buy something until it reaches accounting.
Identify where the process depends on:
- email,
- spreadsheets,
- manual re-entry,
- waiting,
- missing context,
- individual memory.
2. Define Rules and Responsibilities
Clarify:
- who may purchase,
- who may approve,
- what spending thresholds apply,
- what documentation is required,
- how exceptions are handled.
3. Bring Budget Context Into the Decision
If the company checks the budget only after an expense has been posted, it is no longer managing the expense.
It is recording it.
Budget context needs to enter the process before the decision is final.
4. Build the Approval Workflow
Employees should not have to guess who needs to approve an expense.
Managers should not have to search for requests in email or chat.
Rules should automatically send the expense to the correct person.
5. Digitise Documents and Transactions
Receipts and invoices should enter the process early and remain connected to the underlying expense.
6. Connect the Process With Accounting or ERP
The objective is not to introduce another isolated application.
It is to reduce manual handovers between people and systems.
Wflow’s current international product architecture supports this through document intake, AI extraction, approval workflows, ERP/accounting connectivity and digital archiving.
7. Maintain a Digital Archive
After the expense has been processed, the supporting documentation still needs to remain accessible and traceable.
8. Measure What Actually Improved
Useful metrics might include:
- time from expense request to accounting,
- percentage of expenses with missing documentation,
- number of manual interventions,
- approval time,
- exception rate,
- time spent chasing information,
- time until expense data become available to finance.
How Do You Know Your Expenses Are Actually Under Control?
Not by counting how many finance applications the company uses.
A controlled process looks more like this:
- finance knows about significant expenses before the invoice arrives,
- purchasing authority is clear,
- budget context is part of approval,
- transactions have documentation and business context,
- employees know the correct process,
- accountants do not repeatedly re-enter the same information,
- important actions are traceable,
- approved information moves into accounting without unnecessary handovers,
- finance sees spending during the process rather than only after close.
The objective of expense management is not perfectly organised receipts.
It is knowing what the company is spending, why it is spending it, who approved it and what effect that spending has on the business.
Want to Get Your Company Expenses Under Control?
You do not need to replace your entire finance stack.
Start by mapping one expense from the initial request all the way into accounting.
That usually makes it very clear where context, time and control are being lost.
FAQ
What Is Expense Management?
Expense management is the process by which a company plans, approves, records, controls and evaluates its business expenses.
It begins when the need for a purchase arises and continues through approval, payment, documentation, accounting and financial analysis.
What Does Expense Management Include?
Expense management can include purchasing rules, budget context, approval workflows, payment methods, invoices and receipts, document matching, accounting and ERP integration, auditability and reporting.
How Do You Automate Expense Management?
Start by standardising company rules and the approval process.
You can then automate repetitive tasks such as document collection, data extraction, transaction matching, approval routing, validation, reminders for missing documents and transfer into accounting or ERP.
What Is the Difference Between Expense Management and Accounting?
Accounting records an economic event and its accounting impact.
Expense management begins earlier. It determines how the expense is initiated, approved, paid, documented and connected with the information accounting later needs.
Is a Corporate Card an Expense Management System?
No.
A corporate card is a payment method.
It becomes part of an expense-management process when transactions are connected with users, documentation, rules, approvals and accounting.
What Is Expense Management Software?
Expense management software helps companies control the lifecycle of business spending by connecting requests, approvals, payments, documents, accounting data and financial visibility.
The best solution is not necessarily the one with the longest feature list. It is the one that matches and connects the company’s actual process.
How Do You Choose Expense Management Software?
Look at whether the system supports your approval rules, document capture, transaction matching, automation, ERP or accounting integration and traceability.
Also evaluate whether employees can realistically use the process without creating additional administrative work.
Text updated: November 2026

What Is Digital Accounting? The Complete Guide for Modern CFOs
Digital accounting provides a way to gain greater control over finances, accelerate decision-making, and eliminate manual work that slows down finance teams. The combination of modern digital accounting software and accounting automation tools enables CFOs to transform finance operations gradually and realistically—without disrupting daily business operations.
Digital accounting is not the same as automation. Digitalization creates the digital environment and the data. Accounting automation goes one step further: it allows parts of the process — such as data extraction, approvals or transfer to ERP — to run according to predefined rules without unnecessary manual intervention.
In this guide, you will learn:
- the difference between digital accounting and accounting automation,
- what belongs to a modern digital accounting process,
- the main benefits of digitalization,
- why digital accounting is becoming more important across Europe,
- how to implement digital accounting step by step,
- where digital accounting is heading next.
What Is Digital Accounting?
Digital accounting means using digital tools to manage accounting documents, data and processes — from document receipt and validation through approval to accounting, archiving and reporting.
Its purpose does not necessarily have to be replacing the existing accounting or ERP system. A digital process layer can simplify everything that happens before posting and ensure that complete, reviewed information reaches the ERP.
Unlike traditional processes based on paper, email and repeated manual data entry, digital accounting makes it possible to connect documents, data, approvals and accounting context more effectively.
What Belongs to Digital Accounting?
A modern digital accounting environment can include:
- digital receipt of invoices and accounting documents,
- structured e-invoicing,
- automated invoice processing and data extraction,
- approval workflows,
- expense management,
- integration with accounting or ERP systems,
- accounting automation,
- digital archiving,
- audit trails,
- reporting and budgeting.
Digital accounting is therefore not one tool. It is a way of connecting individual parts of the finance process so that information already captured once does not have to be repeatedly re-entered, searched for or passed manually between people.
The Main Benefits of Digital Accounting
1. Time Savings Through Automation
Accounting automation reduces the need to manually re-key information from invoices and receipts. Finance teams can spend more time on control, exceptions and analysis instead of administration.
2. Higher Data Quality
Automated processing reduces errors caused by repeated manual entry and helps maintain more consistent input data.
3. Better Expense Control
Continuous approvals and earlier visibility into liabilities can give management a clearer picture of costs during the month rather than only after the close.
4. Faster Financial Close
If documents are processed continuously, month-end and year-end close require less last-minute searching for missing documents and information.
5. Earlier Data for Reporting
Continuous digital processing reduces the time between a transaction occurring and the information becoming available for reporting and decision-making.
6. Audit Trail and Traceability
Every step in the process can have a recorded history. A company can therefore trace who worked with a document, who approved it and what changed during the process.
Why Digital Accounting Is Becoming More Important Across Europe
Digital accounting is increasingly shaped by the move towards structured financial data, electronic invoicing and more connected finance processes across the EU.
The shift is not simply about replacing paper documents. It is about creating data that can move more easily between suppliers, customers, finance teams and accounting systems.
The EU’s VAT in the Digital Age reforms are accelerating this transition. From 1 July 2030, harmonised Digital Reporting Requirements will apply to relevant cross-border B2B transactions and will rely on structured e-invoicing. Domestic e-invoicing requirements can still differ between EU Member States.
For finance teams, this makes one distinction especially important:
Structured invoices improve the quality and usability of incoming data, but they do not design the internal process around those data.
Companies still need to decide:
- who validates the invoice,
- who approves it,
- how exceptions are handled,
- how accounting context is added,
- how the data are transferred into ERP,
- how the document remains traceable afterwards.
That is why digital accounting should be viewed as a connected process rather than as a collection of individual tools.
Which Areas Should a Modern Digital Accounting Process Cover?
Digital accounting does not mean buying one new application. The goal is to connect individual parts of the finance process so that data captured once do not need to be repeatedly re-entered, searched for or manually handed over.
Document Intake and E-Invoicing
Invoices and other accounting documents should enter the company digitally and through controlled channels — whether by email, upload, system integration or as a structured electronic invoice.
Structured e-invoicing makes it possible to work directly with invoice data instead of having to recover those data afterwards from a PDF or paper document.
A structured invoice is only the starting point. See what happens after an e-invoice is received: the company still needs validation, approvals, exception handling, accounting context and transfer into the ERP or accounting system.
Data Extraction and Processing
OCR and AI can identify suppliers, amounts, VAT information, due dates and other data needed for further processing.
Modern automated invoice processing does not end with reading a document. The system can validate information, compare it with previous cases and prepare the document for the next stage of the process.
Approval Workflows
A digital document should not continue travelling between emails, spreadsheets and chats.
Approval workflows allow the system to determine who should approve a document according to amount, department, project, supplier or other company rules.
Expense Management
Digitalization is not limited to supplier invoices. It can also include corporate-card transactions, receipts, employee purchases and travel expenses.
Well-designed expense management connects budgets, approval, payment, supporting documents and accounting into one controlled process.
Integration With Accounting and ERP Systems
Digital accounting should not create another isolated data island.
Approved and validated information should be able to flow into the accounting or ERP system without unnecessary re-keying.
The objective is not to replace a working ERP simply because finance processes are being digitalized. Digital tools should work as a process layer around the existing accounting environment where that makes sense.
Accounting Automation
Once information is digital and systems are connected, routine stages of the process can be automated.
Accounting automation can include document collection, data extraction, matching, approvals, exception handling, preparation of accounting suggestions and transfer into an ERP system.
Digital Archiving and Audit Trail
Documents need to remain accessible and traceable after posting.
Digital archiving provides controlled storage and retrieval, while an audit trail makes it possible to determine who worked with a document, what changed and who approved it.
Reporting and Budgeting
Posting is not the final purpose of digital accounting.
The real value appears when financial information becomes available quickly enough to support management decisions.
Connecting accounting data with reporting and ongoing budget management can help finance teams identify cost development and deviations from plan earlier rather than waiting for the month-end close.
How to Implement Digital Accounting Step by Step
Digital accounting does not have to mean replacing every system at once. It usually makes more sense to work process by process and remove the points where the business loses the most time and context first.
1. Map the Entire Finance Process
Start by looking at how information actually moves through the company today.
Where does a document originate? Who checks it? Who approves it? Where is information re-entered? When does it reach accounting? And when does the CFO finally see it?
Do not look only at the accounting team. Purchasing, employees, managers, approvers and leadership are all part of the process.
2. Identify Where Information Is Handed Over Manually
The biggest opportunities often appear where data travel through chains such as:
email → Excel → PDF → approver → accounting system → reporting
Every manual handover means additional work, delay and a risk that context gets lost.
3. Decide What to Digitalize and What to Automate
Not every digital process needs to be automated.
First, the company needs reliable digital data and clearly defined rules. Automation then becomes useful for repetitive activities such as extraction, matching, approvals or routing.
For a detailed explanation, see our guide to accounting automation.
4. Do Not Replace a Working ERP Just for the Sake of Digitalization
The accounting or ERP system can remain the system of record.
A digital process layer can manage what happens before it: document intake, validation, approvals, expenses, exceptions and traceability — and then pass reviewed information into the ERP.
The objective is not to add more systems. It is to make sure data can move between them without unnecessary manual work.
5. Start With One Clearly Defined Process
A company does not need to digitalize the entire finance function in one project.
Accounts payable is often a suitable starting point because it has a clear beginning and end, and the amount of manual work can be measured relatively easily.
6. Connect the Individual Tools
OCR, electronic approvals, ERP and digital storage do not automatically create digital accounting if they operate independently.
The real benefit appears when information captured once continues through the process without repeated re-entry.
7. Measure the Impact
Before implementation, define a small number of practical metrics, such as:
- processing time per document,
- approval time,
- number of missing documents,
- number of manual interventions,
- number of exceptions,
- time from receipt to posting,
- time until information becomes available for reporting.
Digitalization then stops being an abstract IT project. The business can show exactly which part of the process improved and how much routine work disappeared.
How Can You Tell That Your Accounting Process Needs Digitalization?
Digitalization is not simply a question of company size or invoice volume.
The more useful question is how much manual work and lost context exists between the individual steps of the finance process.
Typical warning signs include:
- accountants regularly chase missing documents,
- the same information is manually entered into several systems,
- invoices and expenses are approved by email or chat,
- nobody can immediately see where a particular document is,
- finance only learns about some expenses after they happen,
- management gets current numbers only after the accounting close,
- audit preparation requires manual searching through documents and their history,
- business growth automatically means more finance administration,
- the company uses several digital tools that do not share context.
The biggest warning sign is not paper. It is a situation in which somebody repeatedly has to search for, check or re-enter the same information.
If administrative work grows faster than the business itself, see also 5 Signs It Is Time to Digitalize Your Accounting Process.
Where Is Digital Accounting Heading Next?
Digital accounting does not end with PDF invoices, cloud storage or electronic approvals.
The next stage is a finance environment in which data increasingly originate in structured form, systems can exchange them directly, and people are involved primarily where control or judgement is required.
Structured E-Invoicing
With the expansion of e-invoicing and networks such as Peppol, companies will increasingly receive invoice information as structured data rather than only as documents intended for people.
Across the EU, domestic e-invoicing requirements differ between Member States. At EU level, ViDA introduces harmonised Digital Reporting Requirements for relevant cross-border B2B transactions from 1 July 2030, based on structured e-invoicing.
Peppol is an important infrastructure for exchanging structured business documents, but it is not the only possible infrastructure across Europe.
E-invoicing still does not solve the entire internal process.
A company continues to need validation, exception handling, approvals, accounting context and ERP integration.
For a practical breakdown, see E-Invoicing and Invoice Workflow: What Happens After Receipt.
AI Is Moving From Reading Documents to Working With Context
The first wave of AI in accounting focused mainly on extracting data from invoices and documents.
The next stage is AI that can understand recurring patterns, prepare accounting suggestions, validate information and highlight where human attention is actually required.
This is the principle behind Wflow Accounting Autopilot, which moves automation from simple document reading towards controlled routine document processing while keeping finance teams responsible for exceptions and decisions.
Finance Is Moving From Retrospective Reporting Towards Continuous Management
The faster information moves through the process, the sooner it can support decision-making.
The goal of digital accounting is therefore not merely to close last month faster.
It is to shorten the time between something economically relevant happening in the business and finance being able to see and work with that information.
Connecting accounting data with budgeting and ongoing reporting is one of the steps from digital administration towards genuinely digital financial management.
Ready to Take Your Accounting to the Next Level?
The combination of an existing accounting or ERP system with modern digitalization and automation tools makes it possible to transform finance processes gradually rather than replacing everything at once.
A simple pilot can quickly reveal where digital accounting can remove the greatest amount of manual work.
Sources
European Commission: VAT in the Digital Age
European Commission: Electronic Invoicing
Deloitte: 2025 Global Human Capital Trends
Gartner: CFO Report 2025
PWC: How AI agents help drive a new finance operating model

7 Key Features of Accounting Digitization Software That Will Take Your Business to the Next Level
In accounting digitization, the real value lies in control, speed, and real-time decision-making. This article outlines 7 key features of accounting digitization software that have a measurable impact on finance team efficiency—from AI-powered data extraction to real-time reporting and ERP integration.
If you are considering the move to digital accounting, it is critical to understand which features truly matter. In this article, we walk through seven features no modern accounting automation software can operate without.
Feature 1: AI-Powered Data Extraction from Invoices and Documents
What it is:
Artificial intelligence automatically reads invoices, receipts, and contracts and extracts key data such as invoice number, due date, amount, supplier, and VAT—without manual data entry.
Why it matters:
Based on consultations with our clients, accountants spend up to 40% of their time manually entering data. AI-powered accounting digitization software reduces this time by up to 90%.
How it works in practice:
An invoice from your Mobile Network Operator arrives by email → AI extracts key data → the system automatically matches the invoice with a purchase order → the invoice is sent for approval → once approved, it is posted into an ERP of your choice.
Wflow advantage:
Wflow uses advanced OCR technology that recognizes handwritten receipts and non-standard invoice formats. Data extraction accuracy exceeds 96%.
Feature 2: Automated Invoice Processing
What it is:
Accounting automation software automatically validates invoices using 3-way matching (invoice vs. purchase order vs. goods receipt), detects duplicates, and flags suspicious transactions.
Why it matters:
According to the Association of Certified Fraud Examiners (ACFE), invoice fraud is one of the most common fraud vectors in companies—including Central Europe. Automated invoice processing significantly reduces fraud risk and ensures every invoice is properly reviewed.
How it works in practice:
A supplier issues an invoice for EUR 5,000 → the system verifies a matching purchase order → compares it with the warehouse receipt → if everything matches, the invoice proceeds to approval → if not, the system flags the discrepancy.
Business impact:
Companies using automated invoice processing reduce error rates and shorten processing times by 40–50%. Wflow clients report time savings of up to 50%.
Feature 3: Digital Document Archiving
What it is:
All invoices, contracts, receipts, and accounting documents are automatically stored in a secure digital archive with full-text search and qualified time stamps.
Why it matters:
Do you know how many years the accounting documents are required to be archived in your country? Digital archiving ensures authenticity, integrity, and readability throughout the document lifecycle.
How it works in practice:
Need a supplier invoice from 2021? Enter the supplier name or invoice number → the system displays it within seconds → download it, share it with an auditor, or forward it to a colleague.
Wflow advantage:
Wflow provides a secure digital archive with ISO 27001 certification, qualified time stamps, and a complete audit trail. Documents are accessible anytime, anywhere.
Feature 4: Real-Time Financial Reporting

What it is:
A dashboard showing the current financial position of the company—unpaid invoices, monthly expenses, and cash flow bottlenecks.
Why it matters:
CFOs need visibility now, not after month-end close. According to Gartner, companies using real-time reporting achieve 30% better cash flow control.
How it works in practice:
The CFO opens the dashboard → sees 15 unpaid invoices totaling EUR 450,000 → three are overdue → clicks into the detail and immediately initiates follow-up.
Business impact:
Real-time financial reporting enables faster decisions, better cash flow planning, and fewer surprises at closing.
Feature 5: Mobile Approval Workflows
What it is:
Managers approve invoices, expenses, and purchase orders directly from their mobile devices—anytime, anywhere.
Why it matters:
In hybrid and remote work environments, mobile access is essential. Invoices should not wait a week for a manager to return to the office.
How it works in practice:
An employee uploads a travel receipt → the manager receives a mobile notification → reviews and approves with one click → the expense is posted and archived automatically.
Wflow advantage:
Wflow offers a native iOS and Android app with offline mode. Approvals work even without internet access; data syncs automatically.
Feature 6: Seamless ERP Integration
What it is:
Accounting digitization software connects to your existing ERP system via API—no ERP replacement required.
Why it matters:
Companies do not want to replace systems they have already invested in. ERP integration ensures automatic data flow without manual imports or exports.
How it works in practice:
An invoice approved in Wflow → automatically posted in ERP of your choice → linked to the digital archive → viewing the invoice in ERP displays the original PDF.
Wflow advantage:
Wflow integrates with 50+ accounting systems and banks using ready-made connectors or open API.
Feature 7: Automated Expense Management
What it is:
Employees photograph receipts using their mobile phones. The system extracts data, matches it with corporate card transactions, and routes it for approval.
Why it matters:
Expense management is often the weakest link in accounting—lost receipts, missing approvals, Excel chaos. Automation eliminates these issues.
How it works in practice:
An employee pays for lunch with a corporate card → photographs the receipt → AI extracts data → the system matches it with the payment → the manager approves → the expense is posted and archived.
Business impact:
Companies automating expense management save 15–20 hours per month and reduce errors by up to 80%.
FAQ
What are the most important features in accounting digitization software?
AI data extraction, automated invoice processing, digital archiving, real-time reporting, mobile approvals, ERP integration, and automated expense management.
How does AI improve accounting digitization?
AI extracts invoice and receipt data automatically, detects duplicates and suspicious transactions, reduces errors by up to 95%, and shortens processing time by 40–50%.
Can accounting digitization software integrate with existing systems?
Yes. Modern accounting automation software integrates with most ERP systems via API or ready-made connectors—no ERP replacement required.
More than 8,000 companies already manage finances without chaos.





Lindt values low error rates and significant time savings
“The Wflow mobile app is the simplest and fastest way to approve invoices. I especially appreciate that I don’t need to turn on my computer for every transaction—just a few taps in the app and everything is taken care of.”

Shoptet introduced its first AI-powered internal processes with Wflow
“Today, we process all incoming documents digitally—from approval to handover to our external accounting firm. Wflow helped us streamline the entire process, improve efficiency, and build a strong foundation for further automation.”



How to get your finances under control
Practical instructions on how to speed up document processing, set up approvals, and get real-time cost insights.
E-Invoicing Is the Beginning. What Internal Process Comes Next?
E-invoicing changes the way an invoice arrives in a company. But the real value comes afterwards: when the invoice is correctly classified, checked, approved, enriched with context and passed into the accounting or ERP system. See how to build and automate the internal process after invoice receipt.
E-Invoicing Is the Beginning. What Internal Process Comes Next?
E-invoicing changes the way an invoice arrives in a company.
Instead of a PDF attachment in an email, it can arrive as structured data that a system can read and process automatically.
That is a major step.
For financial management, however, an equally important question is what happens to the invoice after it arrives.
Who checks it? Who approves it? Who adds the cost centre, project or accounting context? Where are duplicates, suspicious bank-account changes or missing purchase orders detected? And when do the data reach the ERP so finance can actually work with them?
Across Europe, the regulatory journey differs by country. Some Member States already require structured domestic e-invoicing, others are introducing it gradually. At EU level, ViDA will make e-invoicing the basis for digital reporting for relevant cross-border B2B transactions from 1 July 2030. Taxation and Customs Union
If you are still getting familiar with the basics, start with E-Invoicing in the EU: How Peppol Works and Why It Is About Data, Not Documents.
Here, we will look at the next step: the internal process after the invoice arrives.
The Process Does Not End When the E-Invoice Arrives
A structured invoice improves the quality of incoming data.
But it does not create the rules inside your company.
That is why the transition to e-invoicing is a good opportunity to look not only at invoice format, but at the entire document flow from receipt to accounting.
Email Is Not an Accounting Workflow
Email can receive an invoice.
It cannot manage a financial process.
It does not know who should approve an invoice. It does not check whether it matches a purchase order. It does not automatically flag a changed supplier bank account. It does not know that an invoice has been stuck with one person for five days.
And when an auditor or CFO needs to find out exactly what happened to a document, an email thread quickly stops being sufficient.
If approvals are currently scattered across email, chats and informal agreements, see how automated invoice processing can connect approval, data extraction and accounting workflow.
What Should Happen After an Invoice Arrives?
Once an invoice arrives, the document needs to be classified, its type identified, data completed or validated, routed to the right approver, checked for exceptions and prepared for transfer to the accounting or ERP system.
At Wflow, we automate this process through several layers:
1. Smart Inbox
Invoices and documents enter one controlled place instead of remaining scattered across emails, folders and other channels.
2. Classification and Categorisation
The system identifies the document type, supplier, client or other context and prepares the document for the next step.
3. Data Validation and Exception Checks
Better input data do not mean zero risk. Documents still need to be validated, compared and checked for inconsistencies before they reach accounting.
4. Rule-Based Approval
An invoice should automatically reach the right person based on amount, supplier, project, cost centre or type of expense.
5. Transfer to Accounting / ERP
The ERP remains the accounting backbone. Wflow manages the process before the approved and validated data enter the accounting environment.
For companies that want to introduce e-invoicing without replacing their existing systems, see How to Implement E-Invoicing Without Replacing Your ERP.
E-Invoicing and Wflow Accounting Autopilot
E-invoicing improves the input.
Accounting Autopilot manages what happens next.
Its purpose is not to let AI post accounting entries without oversight.
The goal is to move routine work from accountants’ desks into a controlled workflow: collecting documents, classifying them, extracting data, validating information, preparing accounting suggestions and identifying the cases where human input is required.
The accounting team therefore does not need to treat every document in the same way.
Routine cases can move faster, while attention shifts towards exceptions, control and decisions.
You can see the complete workflow in Accounting on Autopilot: AI Takes Over Routine Document Processing.
The boundary between automation and human responsibility is just as important. We cover it in detail in AI in Accounting and Responsibility for Errors.
How to Tell That Your Process Is Not Ready
E-invoicing will expose weaknesses that already exist inside the company.
The warning signs are usually simple:
- invoices get lost in inboxes,
- approvals depend on reminders,
- the accounting team still re-keys data manually,
- the CFO sees liabilities too late,
- it is unclear who approved what,
- exceptions are handled differently every time,
- ERP data only become available when it is already too late to react.
If several of these sound familiar, the problem is not the invoice format.
It is the process around the invoice.
Traceability is especially important: who approved the document, what changed, why it changed and when it moved to the next stage should not depend on somebody finding the right email.
That same principle becomes even more important as more of the process is automated. See AI in Accounting and Responsibility for Errors for more on auditability and human control.
What to Prepare Before E-Invoicing
Before introducing e-invoicing, it is worth setting up several practical things.
Not to make the process more complicated, but to ensure that a structured invoice does not simply end up in the same chaos as today’s PDFs.
- One controlled entry point for all invoices
The principle is simple: invoices should not end up in personal email accounts, random folders or several disconnected team inboxes.
The company needs one place where documents enter and where it is immediately clear what arrived, who sent it, who it belongs to and what stage it is in.
- Expense rules before the invoice arrives
E-invoicing does not solve only the invoice itself.
If the company does not know who can order a service, who approves the expense, which project it belongs to or which budget it consumes, the delay simply moves further down the process.
A prepared company manages the whole expense process, not only invoice receipt.
- Rule-based approvals instead of reminders
An invoice should automatically go to the right person based on amount, supplier, cost centre, project or expense type.
Without these rules, even a structured invoice will get stuck in exactly the same place as a PDF: someone still needs to forward it, chase an approver and explain what needs to happen.
- Checks for duplicates, changed details and suspicious cases
Automation or Accounting Autopilot can perform part of this control, but the company still needs to define what it expects the system to check.
Duplicate invoices, supplier bank-account changes, purchase-order mismatches or unusual amounts should not depend solely on the manual attention of the accounting team.
- Clear exception handling
Standard cases can gradually move through the process faster.
That makes it even more important to define what happens when something is an exception: who deals with it, what information they need, how they decide and when the document returns to the standard workflow.
Otherwise, exceptions simply move outside the system again.
- Audit trail
Knowing that an invoice arrived is not enough.
The company needs to be able to trace who approved it, what changed and why.
Without an audit trail, control still depends on people’s memory and email history.
- ERP integration
The ERP remains the accounting backbone of the company.
Preparing for e-invoicing does not mean replacing it. The objective is to deliver clean, approved and traceable data into the ERP after the workflow before accounting has been completed.
E-invoicing can be introduced without replacing the existing ERP if the integration layer is designed correctly.
- Visibility of liabilities
Design the process so finance can see not only invoices that have already been posted, but also expenses and documents that are still awaiting approval or missing information.
This gives the CFO an earlier view of future liabilities — before they appear in the accounting system — and creates a better basis for managing cash flow and budgets.
E-invoicing sends better data into the company. Wflow helps build the process that knows what to do with them.
FAQ
What Should Happen After an E-Invoice Arrives?
After receiving an e-invoice, the company still needs to determine who takes ownership of the document, who checks and approves it, and how it is passed into accounting or the ERP.
E-invoicing improves input data, but internal workflows, approval rules, exception handling and audit trails still need to be designed separately.
Is It Enough to Receive E-Invoices by Email?
Email can deliver an invoice, but it cannot manage the entire financial process.
It does not manage approval rules, detect duplicates or changed information, handle exceptions or show where an invoice has become stuck.
If e-invoicing is to create genuine value, the company needs a controlled workflow around the structured invoice.
How Does Wflow Help Process E-Invoices?
Wflow helps manage what happens after invoice receipt: one controlled entry point, document classification, data validation, rule-based approvals, exception handling, an audit trail and transfer into the accounting or ERP system.
This means an e-invoice becomes more than a new document format. It becomes part of a controlled financial process.
E-Invoicing Will Change the Economics of Accounting Firms
Accounting firms often grow by adding people: more clients mean more documents, more communication and eventually more employees. But qualified accounting talent is increasingly difficult to secure, while routine work keeps margins under pressure. E-invoicing and Peppol can move some of this low-value work into automated systems and change the economics of accounting firms.
Accounting firms often grow by adding people. A new client means more documents, more communication — and sooner or later, another accountant.
This model is beginning to run into two fundamental problems:
- a shortage of qualified accounting talent,
- and a growing volume of routine work that keeps margins under pressure.
Across Europe, attracting and retaining accounting talent is already a structural challenge. ACCA describes longstanding skills and talent shortages in the profession, while its European talent research also points to considerable employee mobility and retention pressure. (source: ACCA Global)
But the capacity pressure on accounting firms is no longer just a recruitment issue.
Technology, automation and AI are changing which parts of accounting work genuinely require qualified people — and which parts can increasingly be handled by systems.
Value the Time of Scarce, Qualified People
Not every new client creates the same workload for an accounting firm.
One client delivers documents on time and in the right format. Another requires searching, reminders, manual sorting and repeated corrections.
All of this consumes accounting capacity that should be used for higher-impact work: ensuring accounting accuracy, resolving exceptions, improving data quality, checking VAT treatment, communicating with clients, preparing the close or explaining unusual costs.
The real capacity of an accounting firm therefore depends not only on the number of clients, but on how much manual work each client creates.
If accountants are difficult to recruit, the main question is no longer only “Where do we find another person?”
It is also: “What kind of work are we using the people we already have for?”
E-Invoicing Reduces Part of the Input Chaos
The EU defines an electronic invoice as an invoice that has been issued, transmitted and received in a structured electronic format that allows for its automatic and electronic processing.
For accounting firms, the crucial word is structured.
An invoice no longer has to arrive only as a PDF that somebody opens, reads and re-enters.
Increasingly, it can arrive as data that a system can read, validate and pass into the next stage of the process.
That can reduce some of the work that currently consumes accounting firms’ time:
- manually re-keying invoice data,
- checking data extracted imperfectly from PDFs,
- searching for basic information,
- sorting documents by client or accounting period,
- repeatedly correcting the same fields.
At EU level, EN 16931 provides the common semantic standard for structured e-invoices. ViDA will make EN 16931-based structured e-invoicing central to intra-EU B2B transactions from 1 July 2030, while domestic requirements can differ between Member States. (source: Taxation and Customs Union)
Peppol is important in this transition as one of the major infrastructures through which businesses and systems can securely exchange structured electronic invoices.
For an accounting firm, however, the practical impact matters more than the infrastructure itself: more invoices can arrive in a form that software can process earlier, more accurately and with less manual input.

E-invoicing, however, cannot end with invoice delivery.
A structured invoice does not tell you whether an expense has been approved, which project it belongs to, who needs to provide context or whether the transaction represents an exception.
That is why the value of an accounting firm will increasingly lie in the process around the document, not simply in processing the document itself.
Where the Real Value of an Accounting Firm Lies
Accounting firms do not need to recruit more people simply so they can continue re-keying information, correcting the same errors and chasing clients for missing details.
They need to protect the capacity of qualified accountants for work that creates real value for the client.
E-invoicing can help by moving part of the input routine from accountants’ desks into the system: an invoice arrives as structured data rather than as a document that first needs to be manually interpreted.
Ardent Partners reported that the average AP organisation spent USD 9.40 to process a single invoice in 2024, including invoice receipt, processing, approval, people, technology and operating costs.
This is not a European accounting-firm benchmark, so it should not be read as one. But it illustrates an important principle: every manual intermediate step has a cost — and that cost multiplies with document volume.
A similar principle can be seen in the case of accounting firm SMEyo.
This was not an e-invoicing implementation. It was a digitalisation project for document processing with Wflow.
Documents stopped being manually sorted and physically searched for. Instead, they were automatically stored, extracted and prepared for further processing.
The result was a 70% time saving per document, allowing senior accountants to spend more time on professional work rather than invoice re-keying.
What Accounting Firms Should Do Now
Preparing for e-invoicing does not have to begin with a technical implementation.
The first step should be an audit of the current process.
An accounting firm should map out for its clients:
- how documents arrive,
- how many channels each client uses,
- where information is missing,
- who approves expenses,
- which errors occur repeatedly,
- how much work happens before actual accounting begins,
- which steps should be handled by software.
The audit has one main purpose: identify where accountants’ time is being wasted unnecessarily.
Not everything can be automated immediately.
But it often becomes clear very quickly that a significant amount of work does not arise because the accounting itself is difficult. It arises because of poorly designed document flows between the client, approvers and the accounting firm.
Only then does it make sense to address automated document intake, classification, approvals, audit trails, exception handling and transfer into the accounting system.
For firms that want to go further than invoice intake alone, Wflow Accounting Autopilot shows how AI can automate routine document processing while keeping accountants in control of exceptions and decisions.
Wflow Makes Accounting Firms More Efficient
Wflow helps accounting firms reduce the amount of manual work between the client, the document and the accounting system.
Documents are collected in one place, automatically classified and enriched with the necessary context.
They are sent for approval, checked and passed on into the accounting process.
This means accounting teams spend less time searching through emails, chasing clients and manually checking which documents are ready for processing.
For the broader direction of this development, see also Accounting Routine Belongs to AI. Decision-Making Stays Human.
Want to find out where your accounting firm loses the most time before the actual accounting work even begins?
Let’s look at the document flow from your clients to the accounting system and identify where Wflow can help with intake, approvals, control and exception handling.
Why CFOs Need to Understand Peppol — Even If They Never Use It
CFOs do not need to use Peppol or understand its technical configuration. But they should understand what structured e-invoicing means for financial management: when liabilities become visible, how reliable reporting data are, how quickly approvals happen and whether e-invoicing genuinely improves the process rather than simply meeting regulatory requirements.
CFOs do not need to understand every technical detail of e-invoicing and Peppol. They do not need to know exactly how a Peppol Access Point works, how every data field is formatted or how different technical specifications for electronic documents compare.
But they do need to understand what happens to invoice data after introducing e-invoicing and Peppol — and how to turn that change into an advantage for the business.
E-invoicing represents a broader shift from invoices as documents to invoices as structured data. Peppol is one of the major infrastructures enabling the exchange of this data between businesses and systems.
>> Further reading: What Is Peppol? Why E-Invoicing Is Moving From Documents to Data
The European context matters here. Member States have different domestic e-invoicing requirements, while the EU’s ViDA reform introduces mandatory e-invoicing-based digital reporting for relevant cross-border B2B transactions from 1 July 2030. Peppol is an important European exchange network, but it is not the only permitted infrastructure across the EU.
For CFOs, e-invoicing and Peppol matter because they can change the moment when invoices become usable financial data. That affects when a company sees its liabilities, how quickly it can work with costs and how reliable its data are for decision-making.
CFOs Don't Need to Know How Peppol Works Technically
In many companies, invoices still arrive primarily as PDFs. Someone opens, reads, re-enters, forwards, approves and posts the invoice — and only then does it become part of the financial picture.
Until that point, it may be sitting in an inbox, a folder, an approval queue or simply in someone’s head.
Structured e-invoicing changes this principle. Instead of arriving only as a document intended for a person, an invoice can arrive as structured data that a system can read immediately , validate and feed into the next process.
The European e-invoicing standard EN 16931 defines a common semantic data model for core invoice information, supporting interoperability between systems.
And that is a CFO issue. Not the technical format itself, but its impact on the quality and availability of financial data.
Four Reasons Why E-Invoicing and Peppol Matter to CFOs
1. Data Quality
When an invoice arrives as structured data, the company becomes less dependent on manual re-entry.
That alone does not guarantee perfect accounting, but it creates a better starting point: more consistent information about suppliers, amounts, due dates, VAT and invoice line items.
For CFOs, data quality is fundamental. If the inputs are inaccurate, reporting will always be a more sophisticated interpretation of a flawed foundation.
Peppol can help move invoices from documents that someone has to read into data inputs that systems can process earlier and more consistently.
2. Faster Decision-Making
Financial management often suffers because even when a company has good data, those data only become visible after the fact.
Liabilities enter the financial picture only after manual processing, approval or posting. Costs become visible retrospectively. Reporting waits for the end of the process rather than showing what is happening in the business as it happens.
Structured e-invoicing can bring that moment forward.
If an invoice arrives as structured data and the company has the right workflow in place, a liability can become visible before it appears in the month-end close.
3. Cash Flow Visibility
For a CFO, an invoice is not merely an accounting document. It represents a future cash outflow.
The later an invoice enters the system, the longer the company manages cash flow using an outdated picture.
The liability already exists, but it is not visible in the right report. The supplier is waiting for payment, yet finance may not have a clear view of what has been approved, when payment is due or who is responsible.
Structured e-invoicing can improve liability visibility, but only when it is connected to invoice approvals and accounting workflows and reporting.
Otherwise, only the delivery method changes — not how the company manages its money.
4. Process Control
For CFOs, Peppol can be the starting point for much better control over what actually happens to invoices inside the business.
It becomes easier to understand who approved an invoice, where a process stalled, which documents are waiting for an exception to be resolved, which liabilities have already arisen and where risks or delays are accumulating.
Combined with Wflow, structured e-invoicing can become part of a wider control layer across the financial process.
The CFO no longer needs to wait until documents have been manually located, re-entered and posted. They can monitor the process continuously and manage finance based on what is happening now, rather than only after the month-end close.
The Biggest Risk: Delegating Peppol as a Purely Technical Project
If a company implements structured invoice reception, meets the relevant requirements but changes almost nothing internally, it misses an opportunity to make its accounting and finance operations more efficient.
Invoices still sit in queues. Approvals remain difficult to track. Cost centres are still completed manually. And CFOs continue receiving data too late, even though invoices now arrive through a more modern channel.
IT can handle the integration, but finance leadership must define the operational outcome the change is supposed to deliver.
- Will we see liabilities earlier than we do today?
- Will we reduce manual accounting work between invoice receipt and posting ?
- Will the quality of reporting data improve?
- Will invoice approvals become faster?
- Will we have a clear audit trail and accountability for financial decisions ?
- How will exceptions be handled?
These questions matter more than the technical configuration. E-invoicing creates an opportunity for CFOs to improve how their company is managed.
Want to find out whether your company treats e-invoicing as a format requirement or an opportunity to improve its financial processes?
Let’s examine your current invoice workflow and identify where structured data could deliver faster approvals, stronger control and clearer reporting.
FAQ
Why Should CFOs Care About Peppol?
CFOs do not need to understand Peppol’s technical configuration, but they should understand its impact on financial management.
Peppol can influence when invoice data become available, how quickly liabilities become visible, how reliable reporting inputs are and how much manual work remains between invoice receipt and accounting.
Is Peppol Just a Technical Topic for IT or Accountants?
IT, the accounting team or a software provider can handle the technical integration.
But the CFO should determine what the change must achieve for the business: faster approvals, better liability control, higher-quality reporting, an audit trail and less dependence on manual invoice processing.
How Is Peppol Related to E-Invoicing?
E-invoicing is the broader shift towards invoices in structured, machine-readable form.
Peppol is an infrastructure that enables the secure exchange of structured electronic documents between businesses and systems.
For CFOs, what matters most is what happens to invoice data once they reach the company.
Is Peppol Mandatory Across Europe?
No. E-invoicing requirements vary by country and transaction type. The EU’s ViDA reform introduces harmonised requirements for relevant cross-border B2B transactions from July 2030, but does not make Peppol the sole mandatory transmission network.
Approve expenses and manage documents anytime, anywhere
Approve expenses, upload documents and keep track of costs in real time, directly from your mobile.